
Secured equipment loan
Often called a chattel mortgage, this lets the business own equipment while the lender holds security over it. Compare the loan term and any balloon with the asset's useful life and planned replacement date.
Equipment finance to put the right tools and machinery to work. We consider the full purchase, useful life and supplier payment timing alongside your business cash flow.

Equipment finance spreads the purchase cost of eligible machinery, tools and business assets. We assess the equipment, its purpose and your business records, then explain the proposed finance before a formal application.
Earthmoving plant and construction equipment
Manufacturing and workshop machinery
Forklifts and warehouse equipment
Agricultural machinery and implements
Hospitality, medical and practice equipment
Business technology and eligible specialist equipment
Have something in mind? Let’s talk finance.
Get my free quoteStart with how long you need the equipment and whether ownership matters. Then compare the payment commitment and what happens when the agreement ends.
Often called a chattel mortgage, this lets the business own equipment while the lender holds security over it. Compare the loan term and any balloon with the asset's useful life and planned replacement date.
A finance lease gives you use of equipment owned by the financier. Hire purchase provides a path to ownership. Compare the final payment and ownership conditions in each agreement rather than treating both as rental.
Hire can suit occasional demand or testing a service before buying. Check minimum periods, maintenance, usage limits and return costs. Lower initial commitment can mean higher cost over years of regular use.
| Project cost | Funding check | Timing and cash check |
|---|---|---|
| Machine and identifiable attachments | Confirm the accepted asset, condition, supplier, price and security. | Record deposit and balance dates; match finance settlement to supplier release. |
| Freight, installation and software | Ask which line items the proposed facility accepts. Keep exclusions visible. | Identify amounts due before delivery or commissioning and who funds them. |
| Building works and site preparation | Assess separately unless explicitly included in the accepted facility schedule. | Keep the site-ready payment dates separate from equipment delivery. |
| Stock, wages and launch costs | Allow operating cash or assess a suitable separate facility; do not count them as accepted equipment by default. | Set the operating buffer needed after all deposits and project payments. |
Business.gov.au: buying or leasing vehicles and equipment · Business.gov.au: preparing a business loan
Hypothetical cash budget, all amounts on the same GST-inclusive basis: an $80,000 machine, $10,000 attachments, $5,000 freight, $5,000 installation, $15,000 site works and $5,000 stock total $120,000. This example assumes the facility accepts only the machine, attachments and freight, a $95,000 schedule. That assumption is not lender policy.
A $10,000 deposit already paid toward that schedule leaves $85,000 of net equipment funding before finance fees. The other $25,000 of project costs still needs cash. Starting with $60,000 before paying the deposit means $50,000 remains after it; paying the remaining $25,000 leaves $25,000. The total cash contribution is $35,000, counting the deposit once, with $5,000 left above a separately chosen $20,000 operating buffer.
If freight is also excluded, the accepted schedule falls to $90,000, finance falls to $80,000 and total cash needed rises to $40,000. Only the $20,000 operating buffer remains. Confirm deposit and delivery dates as well as totals; this example does not assume a lender will pay before delivery or fund progress claims.
For a replacement, show current use, repair costs or hire bills. For expansion, bring orders, contracts or evidence of demand. Keep forecast assumptions clear and distinguish unsigned opportunities from secured work.
For used equipment, provide the asset description, serial details where relevant, seller records, condition information and the proposed inspection or valuation. The lender's accepted value and term may differ from the purchase price or expected useful life.
For imports or a build, give us the supplier contract, currency, deposit schedule, shipping or build stages and delivery/commissioning requirements. Confirm which stage the proposed lender can fund before relying on finance for an earlier payment.
Let’s compare your options.
Get my free quoteWe check whether a streamlined application fits or whether financial statements give the lender a clearer picture of the business and purchase.
Low doc uses a reduced or alternative document set for a lender's eligible applications. It does not remove credit or business checks. The asset, borrowing amount, trading history and other commitments determine whether it fits. We explain the required evidence without promising a universal dollar limit.
Profit and available cash are different. Existing loan repayments, tax commitments, seasonal receipts or a large installation bill can affect the new repayment. A lender may also need more information about an unusual machine, even when the business itself is trading well.
Lenders assess repayment capacity and the equipment's potential resale value. Explain both with business records and the asset's specification, condition and market. Buying new equipment does not remove the need to establish affordability.
Estimate the payment for the amount you intend to finance, then test a different deposit, term or balloon.
Adjust the amount, term and rate to see an indicative repayment.
Illustration only, not a lender offer. Starts at 6.95% p.a. over five years, with any optional balloon at 0%. Assumes $1,490 in upfront fees financed and $0 ongoing fees. These are modelling assumptions, not actual X Lend or lender charges. Total repayable counts fees and any final balloon once. Weekly and fortnightly figures are monthly-payment equivalents.
The calculator models your inputs, not a lender offer. Check actual fees, repayment frequency and tax treatment in the proposed finance. The starting rate is illustrative.
Allow for servicing, consumables and downtime. A balloon reduces regular repayments but leaves a final commitment. Consider replacement timing rather than assuming a future equipment sale will cover it.
Find my optionsThe machine might be the biggest item on the quote, but it is rarely the whole project. Installation, site works, opening stock and wages can create a cash gap even when the equipment is covered.
We connect replacement needs, hire savings or added capacity with evidence of the work behind the purchase.
An itemised quote shows which costs the lender accepts and what cash you need separately.
We check deposits, build stages and delivery dates against when the lender can release funds.
Send us an itemised budget and each supplier's payment dates. We separate the proposed asset schedule, costs that need lender confirmation and cash needed before the equipment starts earning.
Business.gov.au: buying or leasing vehicles and equipment · Business.gov.au: preparing a business loan
The existing excavator failed during a major job and the available replacement was a used private-sale machine that needed to settle quickly.
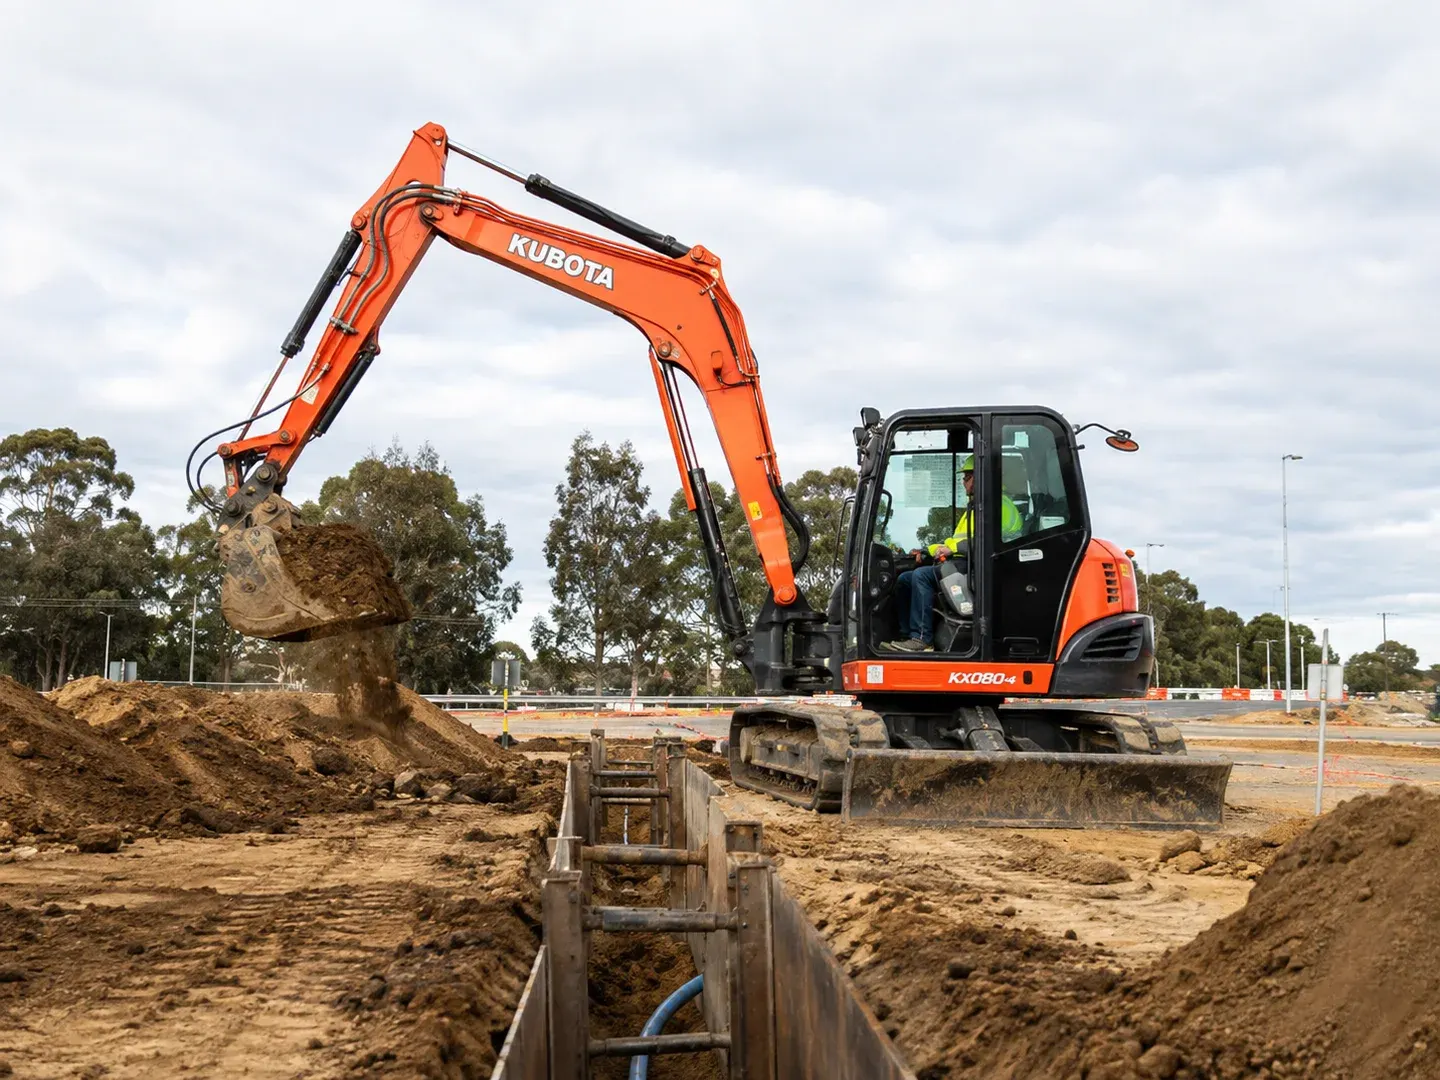 Excavator finance · Wollongong, NSW
Approved on the first lender enquiry and settled at a historical rate of 9.95%, quickly enough to keep the active project running.
Historical customer outcome. Vehicle and business images are illustrative.
Find out what’s possible for you.
Get my free quoteCompare finance with buying outright and hiring over the period you actually expect to use the equipment.
Keep operating cash available while replacing essential equipment.
Own an asset you expect to use regularly over several years.
Reduce reliance on repeated hire, where total ownership costs support that decision.
Hire can fit a short project or uncertain workload without a long repayment commitment.
Cash avoids borrowing costs if enough remains for operations and repairs.
Waiting may make sense when installation, staffing or customer demand is not ready.
We organise the application around the asset and the supplier's timetable.
Send the itemised quote, delivery date and explanation of the work the equipment will do. Flag deposits, imports or progress payments.
We assess the asset and business records, then explain the proposed costs, repayments, security, funding gap and any lender or director-check requirements before an application.
Once you choose an option, we explain the selected application, required credit enquiries and assessment conditions. With your authority, we prepare the evidence and work through the lender assessment.
We coordinate final invoices, asset checks, signed documents and the lender's payment conditions. Confirm delivery and acceptance requirements before arranging collection or installation.
Tell us what you need and where things stand. We explain suitable options and the proposed costs before you choose whether to apply.
Finance is our core service. We do not routinely promote insurance or warranties. We only assist with these when a customer specifically asks. How we work.
I had a great experience working with Corey and couldn’t recommend him highly enough. He went above and beyond to help me throughout the process, providing valuable guidance and advice on how to improve my chances of approval. Corey is extremely knowledgeable, experienced, efficient and his communication was excellent from start to finish. He kept me informed at every stage, always approachable and was never difficult to get in touch with whenever I had questions.
I had a great experience dealing with Corey and the finance team. Corey was professional, friendly, and extremely helpful throughout the entire process. He made everything straightforward, communicated clearly, and went above and beyond to make sure everything went smoothly. His knowledge, efficiency, and excellent customer service made the whole experience stress-free. I highly recommend Corey and the team to anyone looking for reliable and professional finance services. Thank you, Corey, for your outstanding service!
Really happy with the service I received from Corey. Before speaking with Corey, I’d already been knocked back by THREE other places and was honestly starting to think getting finance wasn’t going to happen!! Corey took the time to understand my situation and actually put in the effort to help me out. He was easy to deal with, kept me updated throughout the whole process and was always happy to answer any questions I had. What I appreciated most was that he didn’t just brush me off like the others. He genuinely went out of his way to help and made the whole process a lot less stressful. Couldn’t recommend Corey enough. Thanks again mate, really appreciate everything you’ve done for me and making my dream come true!
Let us help with
equipment finance.
The details you want to know before taking the next step.
Some lenders assess newer businesses. Industry experience, available cash, contracts and evidence of work help explain the proposal. Separate established activity from forecasts before committing to the purchase.
Some lenders accept auction purchases. Send the listing, buyer fees and payment deadline before bidding. Confirm the specific lot and settlement conditions with us; an initial discussion does not make the bid conditional on finance.
No. The PPSR records security interests, not ownership. The appropriate search depends on the equipment and seller. We also need seller and purchase documents, and any existing financier's payout arrangements. Asset inspection is a separate check.
Tax treatment depends on the structure, business use and rules that apply to your business. A loan, lease and hire purchase can be treated differently. Have your accountant confirm GST, deductions and depreciation before relying on a tax saving in the budget.
Ask for a current payout or termination figure and compare it with the equipment's sale or trade-in value. Fees and a remaining balloon can change the result. Tell us your expected upgrade timing before choosing the original finance term.
It may be possible, depending on the assets and lender. Provide each quote and delivery date. We check whether one facility or separate settlements makes sense and identify any deposits or invoices that cannot be funded together.
No. With your written authority, we can obtain your personal credit report as an authorised access seeker. This records file access rather than a credit application enquiry and does not affect your score. A formal lender application and credit enquiry only follow once you authorise them.
Equifax: soft and hard credit checks · OAIC: credit reporting terms

Reviewed by Corey Marino
FBAA member M-354085 · Diploma-qualified finance broker · Last reviewed 25 October 2026 · Content updated