Pay interest only on what you use
The limit sits ready; you're only charged on the funds you actually draw down.
Be ready when your business needs funds. We’ll explore our 80+ lender panel for suitable credit facilities and explain limits, fees and repayments clearly.

A line of credit is the all rounder of business finance. It's commonly used to:
Bridge gaps while you wait on debtors
Fund stock and inventory runs
Cover payroll and tax in quiet months
Take advantage of supplier discounts
Smooth seasonal peaks and troughs
Handle unexpected costs and repairs
Fund a short term growth push
Keep a standing buffer for peace of mind
The purpose and timing of the business lines of credit requirement help determine the amount, repayment period and facility type that may fit.
These terms describe how business lines of credit can be accessed and repaid. We explain which features apply to each compared option.
These records connect recent trading and existing commitments with the cash expected to meet the business lines of credit repayments.
Have something in mind? Let’s talk finance.
Get my free quoteSome months you're flush, some months you're funding stock and waiting on debtors. A line of credit gives you a preapproved limit you can dip into whenever you need, then repay as the cash comes back. X Lend is a finance broker: we take one application and compare it across 80+ banks and nonbank lenders to set up the right finance option.
The limit sits ready; you're only charged on the funds you actually draw down.
Draw, repay and draw again as you trade, the limit refreshes without reapplying each time.
We compare banks and specialist lenders in one go to set the right limit at the right price.
Unlike a term loan, you only pay interest on what you actually draw, so the finance option can sit ready at no cost until the day you need it. Draw down for a stock run or a quiet month, repay when the invoices land, and the limit refreshes for next time.
We match the limit and structure to how your business trades, whether it's secured against assets or a smaller unsecured line for working capital. We keep the costs plain English and only submit once you're ready.
Back it with assets for a larger limit, or keep a smaller unsecured line for everyday flexibility.
Set the facility up in calmer times so the buffer is there the moment cashflow tightens.
We explain the rate, limit and any line fees upfront so there are no surprises.
Here's the appealing part: interest generally applies only to what you actually draw, so the finance option can sit ready as a buffer, set it up in calmer times and it's there the moment cashflow tightens.
Try an amount and term for your business finance. When you’re ready, we’ll compare the options available to you.
Adjust the amount, term and rate to see an indicative repayment.
Estimate only. Calculations include an assumed $990 broker origination fee and $500 lender fee, both financed. Total repayable includes those fees, interest and any final balloon. Weekly and fortnightly figures are equivalents of the monthly estimate. Actual fees and repayment timing depend on your offer.
Your quote takes your circumstances and finance requirements into account. Compare your rate, fees and repayments together before choosing an offer.
Find my optionsThe business needed to buy materials at the start of each commercial project but did not receive progress payments until later stages.
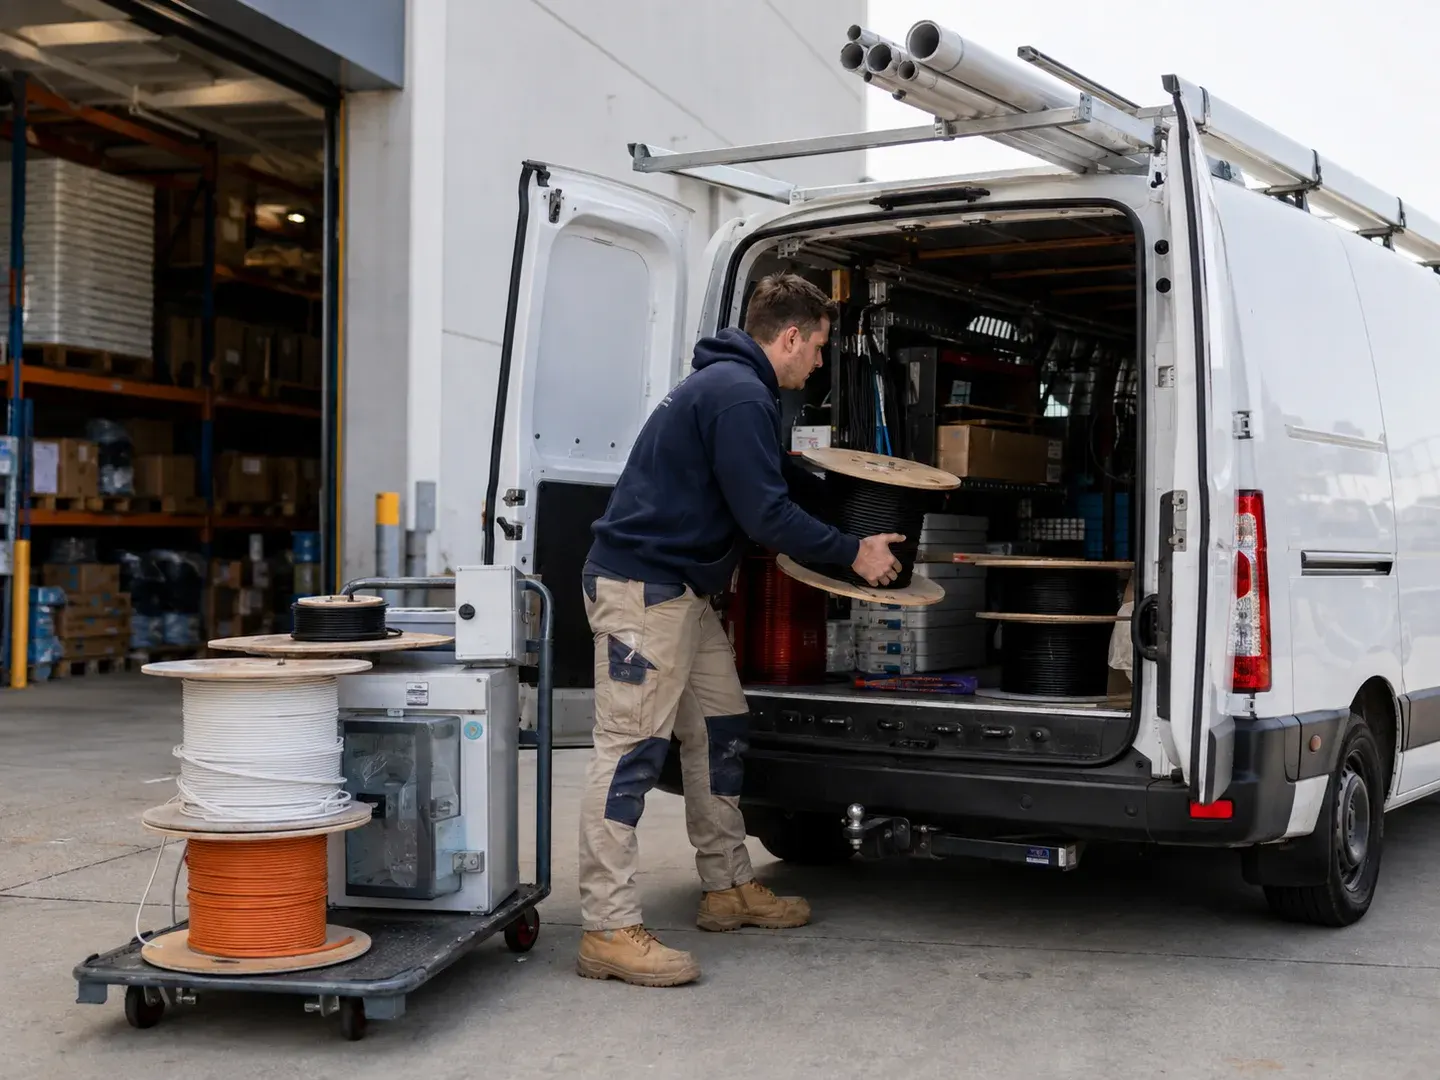 Business line of credit · Canberra, ACT
Approved on the first lender enquiry and settled with a $60,000 limit. Interest applied only to the amount in use, creating an ongoing project cashflow buffer.
Historical customer outcome. Vehicle and business images are illustrative.
Find out what’s possible for you.
Get my free quoteWe match your circumstances to suitable lenders for business finance. Your broker helps you prepare the application.
A business lines of credit assessment connects the business purpose and timing with recent trading, existing commitments and a credible repayment source. The sections below show the structures and records relevant to that decision.
Your broker handles the lender comparison and paperwork for business finance, keeping you informed at each step.
Tell us what you want to finance, how much you need and when you need it. That could include bridge gaps while you wait on debtors.
We help organise bank statements and BAS and check the lender criteria that apply to your circumstances to find lenders that fit your situation.
We explain the available rate, term, repayment and security options, including the full cost and how repayments fit your budget. You choose the option to take forward.
Your broker coordinates lender conditions, signed documents and payment details, so you can focus on what comes next.
Your broker reviews your enquiry and explains the next steps, usually within one business day. An enquiry does not create a credit check or an obligation to proceed.
Compare the ways you can arrange business finance, with a broker to explain your options.
The facility should support a repeatable cash-flow cycle with a clear pathway for the balance to return toward zero. Renewal conditions and fees on unused limits also belong in the comparison.
Base the limit on the maximum evidenced gap and its expected repayment pattern.
Review establishment, line, non-utilisation and renewal fees as well as the interest margin.
Without a reduction plan, a convenient facility can become long-term expensive debt.
Some lenders periodically review limits, financial information and account conduct.
A line of credit suits recurring timing gaps where funds are drawn and repaid across the operating cycle. The approved limit should reflect realistic peak how much the asset will be used.
A week-by-week business lines of credit forecast can place wages, supplier bills, tax, expected receipts and the proposed repayment on one timeline. This exposes the peak cash requirement and its expected repayment source.
For business lines of credit, signed contracts, customer orders, aged receivables and payment schedules can show the amount and timing of expected revenue. Heavy reliance on one customer may need further explanation.
Recent bank statements, BAS, internal accounts and accountant information can support a business lines of credit assessment when the latest annual financial statements no longer reflect current trading.
Illustrative examples of how we approach business finance.
Supplier payments regularly fall before customer receipts.
We measure the peak gap across several months and compare revolving finance options sized to that pattern.
Bank statements, supplier terms, aged receivables and monthly forecast.
Mobilisation costs for new work arrive while existing projects await progress payments.
We combine the project calendars and identify the maximum temporary funding requirement.
Contracts, milestone schedules, job-cost reports and progress claims.
Growth has increased regular how much the asset will be used of the current finance option.
We review actual drawdown history and compare an appropriate limit and fee structure.
Overdraft statements, bank conduct, BAS and current forecast.
At X Lend, we start by matching the funding term to the job the money or asset needs to perform. We then identify the documents and policy issues, choose a suitable lender and ask the customer to approve one considered submission.
Let’s compare your options.
Get my free quoteSee how arranging finance compares with waiting or paying the full cost upfront.
Use business finance for a suitable operating cost, growth opportunity or timing gap.
Assess whether business finance preserves enough working capital for wages, suppliers, tax and day-to-day expenses.
Match the business finance facility structure to the stated business purpose and expected cash-flow cycle.
A project linked to business finance may be missed when funds are not available at the required time.
The cash-flow pressure business finance is intended to address may increase while customer receipts remain delayed.
Self-funding the need instead of using business finance can leave less capacity to absorb an unexpected expense or slow month.
Corey was excellent to deal with. He was able to get me a better rate than everyone else, he was very responsive, worked quickly and made the process very easy, even with me asking a million questions. I would definitely use him again next time.
I can’t recommend Corey from X Lend highly enough. From the very first conversation, he was professional, transparent, and genuinely focused on finding the best outcome for me. Corey took the time to explain every step of the finance process in a way that was easy to understand, answered all my questions promptly, and never once made me feel rushed or pressured. I really appreciated how proactive he was, keeping me updated, following up with lenders, and making sure everything stayed on track. What really stood out was how hard he worked to secure a great deal. He compared multiple lenders, negotiated on my behalf, and ultimately achieved a rate and repayment structure that exceeded my expectations. The whole process of purchasing my car was smooth and stress‑free thanks to their expertise. If you’re looking for someone knowledgeable, reliable, and genuinely in your corner, I wouldn’t hesitate to recommend them. I’ll definitely be using their services again in the future :)
Corey helped me through the entire process of getting my dream family car! He was extremely prompt with his responses and had everything organised quickly and smoothly. I made a huge mistake by settling finance on the wrong car (a 5‑seater instead of a 7‑seater), but Corey was incredibly understanding and supportive. He contacted the dealership, lender, and even rearranged my insurance for me. He did all of this without ever making me feel like a hassle, even though I knew I was being a pain! Despite the setback, Corey stayed fast and efficient, kept me confident throughout the process, and managed to get everything cancelled and re‑approved for a higher amount so I could get my actual dream car. I highly recommend Corey. He speaks to you like a friend and genuinely has your best interests at heart. I already had quotes from Toyota Finance and Toyota Insurance, and Corey was able to get both significantly cheaper. Toyota Finance even reviewed Corey’s figures and confirmed they couldn’t beat them. I will never look to another finance company again.
Let us help with
business finance.
The details you want to know before taking the next step.
We're a finance broker: we compare 80+ banks and nonbank lenders and place your line of credit with the best fit.
Generally no, interest applies only to the funds you draw. Some facilities carry a small line or facility fee to keep the limit open, which we'll spell out upfront.
A term loan gives you a lump sum repaid over a set period. A line of credit is revolving, you draw and repay flexibly up to a limit, paying interest only on the balance you're using.
Both are available on our panel. Securing the facility against assets typically unlocks a larger limit and a sharper rate; an unsecured line trades some of that for flexibility.
Limits depend on your turnover, trading history and any security offered. We'll give you a realistic figure before you apply.
Common examples include revolving working capital, supplier deposits, wage timing, project costs, seasonal purchases, emergency liquidity. This is not a restricted list: the lender will still look at the exact item or purpose, the amount requested and your circumstances.
A lender may ask for bank statements, BAS, aged receivables, cash-flow forecast, contracts, purchase orders. You may not need everything on that list. X Lend confirms what applies before anything is submitted.
For business finance, we first confirm the transaction, timing and available evidence. We then explain the issues that matter, compare lenders whose rules fit those facts and show the proposed option before any application is submitted.
Reviewed by Corey Marino
FBAA member M-354085 · Diploma-qualified finance broker · Last reviewed 24 August 2026