No property security
Borrow on the strength of your business while real estate stays outside the registered security.
Back your next business move. Your broker explores our 80+ lender panel for suitable unsecured funding and explains the costs, repayments and requirements.

An unsecured loan is flexible by design. Businesses use it to fund:
Working capital and cashflow gaps
Hiring and onboarding staff
New premises and fitouts
Stock and inventory purchases
Marketing and growth campaigns
Equipment top ups and repairs
Tax and BAS obligations
Bridging a short term opportunity
The purpose and timing of the unsecured business loans requirement help determine the amount, repayment period and facility type that may fit.
These terms describe how unsecured business loans can be accessed and repaid. We explain which features apply to each compared option.
These records connect recent trading and existing commitments with the cash expected to meet the unsecured business loans repayments.
Have something in mind? Let’s talk finance.
Get my free quoteSometimes the opportunity comes before the cash does, a new premise, a bigger team, a marketing push or a stock run. X Lend is a finance broker: we take one application and compare it across 80+ banks and nonbank lenders to access an unsecured business loan that funds the move without putting your home or property on the line.
Borrow on the strength of your business while real estate stays outside the registered security.
We compare banks and specialist nonbank lenders in one go for the best fit and rate.
Unsecured facilities move quickly, many are approved and funded within a couple of business days.
An unsecured business loan is assessed on business strength and leaves real estate outside the registered security. We match the finance option to turnover, cash flow and time in business to find a suitable structure.
Because we compare the whole panel, we can place deals a single bank might decline, and we're upfront about what's realistic before you apply. We explain the rate and repayments in plain English and only submit once you're ready.
Working capital, expansion, hiring, stock or marketing, it's your call how you deploy it.
Weekly, fortnightly or monthly structures matched to how the money comes in.
We tell you what's achievable before you apply, so you don't waste an enquiry.
Your home stays outside the registered security. Lenders assess trading performance, many finance options can fund within 48 hours of approval, and some lenders consider businesses with as little as six months' trading.
Try an amount and term for your unsecured business loans. When you’re ready, we’ll compare the options available to you.
Adjust the amount, term and rate to see an indicative repayment.
Estimate only. Calculations include an assumed $990 broker origination fee and $500 lender fee, both financed. Total repayable includes those fees, interest and any final balloon. Weekly and fortnightly figures are equivalents of the monthly estimate. Actual fees and repayment timing depend on your offer.
Your quote takes your circumstances and finance requirements into account. Compare your rate, fees and repayments together before choosing an offer.
Find my optionsThe business had won a large supply order but needed to pay the manufacturer before receiving payment from its customer.
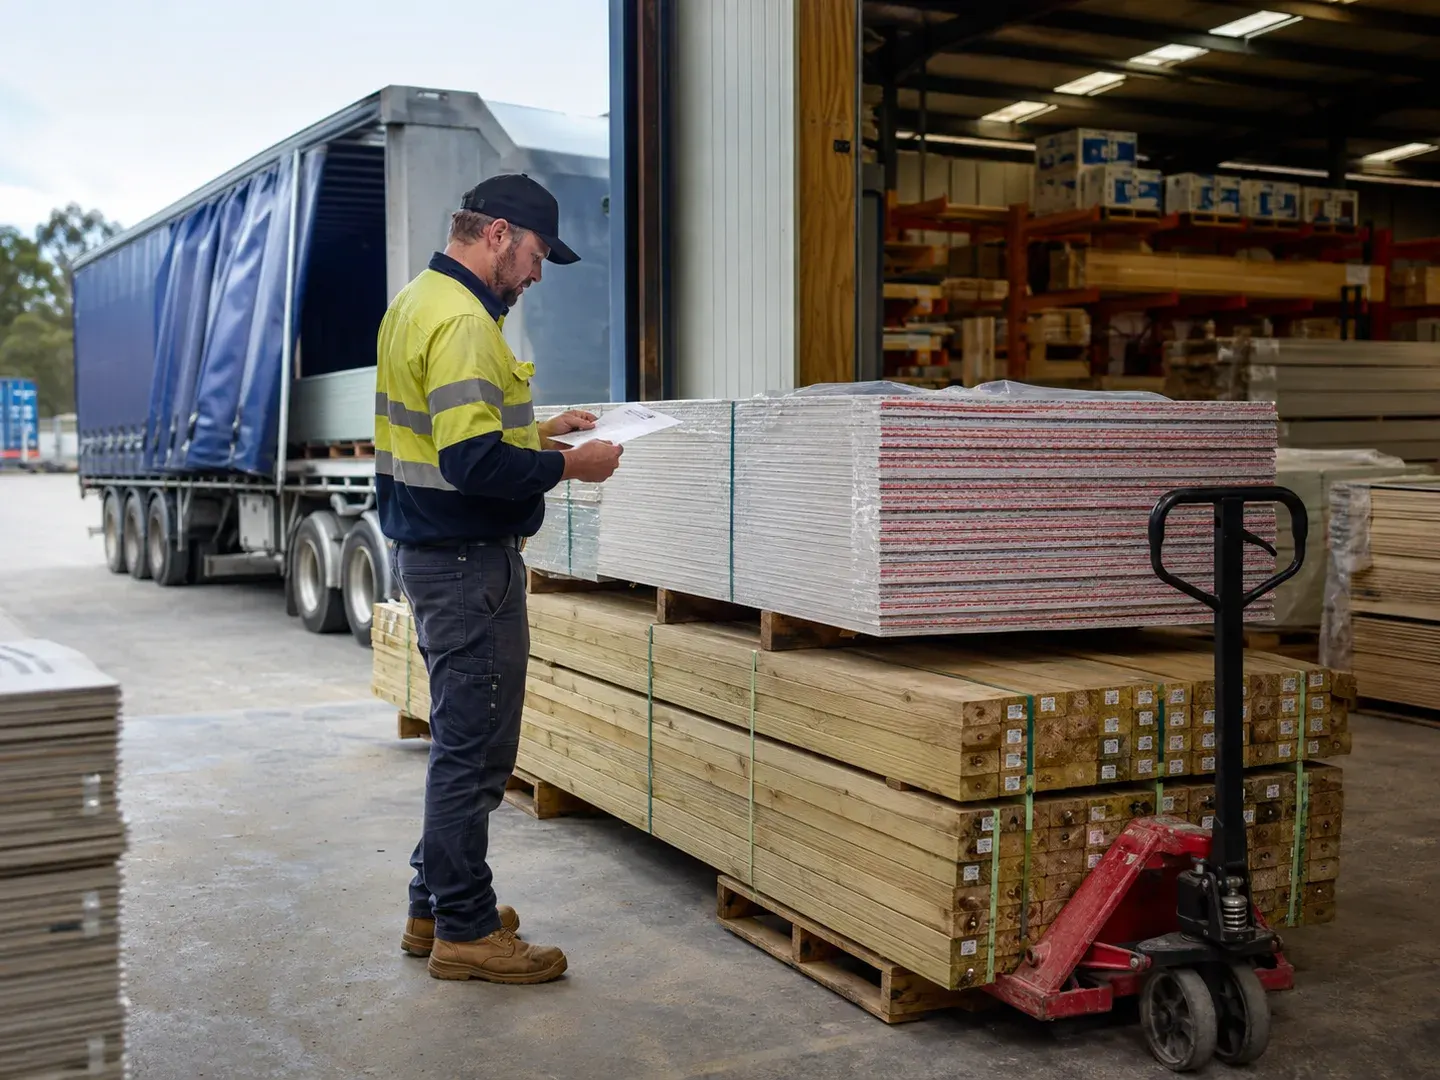 Unsecured business loan for stock · Brisbane, QLD
Approved on the first lender enquiry and settled for $65,000 at a historical rate of 17.49%, allowing the stock to be ordered immediately and the customer contract to be fulfilled.
Historical customer outcome. Vehicle and business images are illustrative.
Find out what’s possible for you.
Get my free quoteEvery lender sets its own rules, but this is what most of the panel wants to see:
Many lenders want 12 months of trading and some panel lenders consider businesses from around six months. We route your application to lenders whose policy fits your trading stage.
A quiet quarter can spook a lender that only reads the last few statements. We add the context, seasonality, a lost then replaced contract, and place the deal with lenders who read the fuller picture.
Several existing short term facilities running at once is a red flag for most funders. Often the answer is consolidating them into one cleaner facility first, which we can arrange.
It's rarely the tax debt itself that sinks a deal, it's arrears with no plan. A documented arrangement with the tax office changes the conversation, and some lenders will even fund the payout.
An old default with a good story behind it doesn't have to be fatal. We package the explanation upfront so it's answered before it becomes an objection.
A unsecured business loans assessment connects the business purpose and timing with recent trading, existing commitments and a credible repayment source. The sections below show the structures and records relevant to that decision.
Your broker handles the lender comparison and paperwork for unsecured business loans, keeping you informed at each step.
Tell us what you want to finance, how much you need and when you need it. That could include working capital and cashflow gaps.
We help organise driver licence for each director and your ABN and basic business details and check an active ABN, typically registered for at least 6–12 months depending on the lender to find lenders that fit your situation.
We explain lump sum term loan and shorter, sharper terms, including the full cost and how repayments fit your budget. You choose the option to take forward.
Your broker coordinates lender conditions, signed documents and payment details, so you can focus on what comes next.
Your broker reviews your enquiry and explains the next steps, usually within one business day. An enquiry does not create a credit check or an obligation to proceed.
Unsecured doesn't mean one size fits all. These are the structures we arrange most often:
The classic: a set amount upfront, repaid over an agreed term. Clean and predictable for a defined project like a fitout or a hiring round.
Unsecured terms typically run from around 3 months to 5 years, so you're not still carrying the debt long after the opportunity has paid for itself.
Daily, weekly, fortnightly or monthly, we match the frequency to how cash actually arrives, so repayments never collide with payroll.
Most unsecured loans use a director's guarantee while property stays outside the registered security. The guarantee is a real commitment, and we explain it before anything is signed.
If you own equipment or vehicles outright, some lenders will secure against those instead, often trimming the rate without touching real estate.
Many lenders allow early payout, and some discount the remaining interest when you do. We favour those terms wherever your plans might change.
Flexibility and faster documentation can be useful, but the amount, term, fees, repayment frequency and guarantee position require careful comparison.
Personal or director guarantees may apply and should be understood before signing.
Daily or weekly repayments can feel different from a monthly figure and should be mapped against receipts.
Short-term finance is generally a poor match for benefits expected over many years.
Compare the headline rate with establishment, ongoing, early-repayment and default costs, using the same loan amount, repayment frequency and term for each option.
The finance option should match the cash benefit and repayment period of the purpose. Short-lived expenses usually call for a shorter repayment horizon than long-term expansion assets.
A week-by-week unsecured business loans forecast can place wages, supplier bills, tax, expected receipts and the proposed repayment on one timeline. This exposes the peak cash requirement and its expected repayment source.
For unsecured business loans, signed contracts, customer orders, aged receivables and payment schedules can show the amount and timing of expected revenue. Heavy reliance on one customer may need further explanation.
Recent bank statements, BAS, internal accounts and accountant information can support a unsecured business loans assessment when the latest annual financial statements no longer reflect current trading.
Illustrative examples of how we approach unsecured business loans.
The business needs inventory before the related customer receipts arrive.
We map purchase dates, expected stock turn and sales history, then compare terms that fit the time between paying costs and receiving customer money.
Supplier invoice, sales history, bank statements and stock forecast.
A signed contract creates upfront wage, material and setup costs.
We prepare a milestone calendar and show the amount needed before income arrives between mobilisation and the first progress claim.
Signed contract, head contractor agreement, purchase orders and cash-flow forecast.
Recent revenue has grown since the latest financial year.
We combine current alternative records and select lenders that assess the present trading position.
BAS, bank statements, management accounts and accountant confirmation.
At X Lend, we start by matching the funding term to the job the money or asset needs to perform. We then identify the documents and policy issues, choose a suitable lender and ask the customer to approve one considered submission.
Let’s compare your options.
Get my free quoteSee how arranging finance compares with waiting or paying the full cost upfront.
Use unsecured business loans for a suitable operating cost, growth opportunity or timing gap.
Assess whether unsecured business loans preserves enough working capital for wages, suppliers, tax and day-to-day expenses.
Match the unsecured business loans facility structure to the stated business purpose and expected cash-flow cycle.
A project linked to unsecured business loans may be missed when funds are not available at the required time.
The cash-flow pressure unsecured business loans is intended to address may increase while customer receipts remain delayed.
Self-funding the need instead of using unsecured business loans can leave less capacity to absorb an unexpected expense or slow month.
Corey was excellent to deal with. He was able to get me a better rate than everyone else, he was very responsive, worked quickly and made the process very easy, even with me asking a million questions. I would definitely use him again next time.
I can’t recommend Corey from X Lend highly enough. From the very first conversation, he was professional, transparent, and genuinely focused on finding the best outcome for me. Corey took the time to explain every step of the finance process in a way that was easy to understand, answered all my questions promptly, and never once made me feel rushed or pressured. I really appreciated how proactive he was, keeping me updated, following up with lenders, and making sure everything stayed on track. What really stood out was how hard he worked to secure a great deal. He compared multiple lenders, negotiated on my behalf, and ultimately achieved a rate and repayment structure that exceeded my expectations. The whole process of purchasing my car was smooth and stress‑free thanks to their expertise. If you’re looking for someone knowledgeable, reliable, and genuinely in your corner, I wouldn’t hesitate to recommend them. I’ll definitely be using their services again in the future :)
Corey helped me through the entire process of getting my dream family car! He was extremely prompt with his responses and had everything organised quickly and smoothly. I made a huge mistake by settling finance on the wrong car (a 5‑seater instead of a 7‑seater), but Corey was incredibly understanding and supportive. He contacted the dealership, lender, and even rearranged my insurance for me. He did all of this without ever making me feel like a hassle, even though I knew I was being a pain! Despite the setback, Corey stayed fast and efficient, kept me confident throughout the process, and managed to get everything cancelled and re‑approved for a higher amount so I could get my actual dream car. I highly recommend Corey. He speaks to you like a friend and genuinely has your best interests at heart. I already had quotes from Toyota Finance and Toyota Insurance, and Corey was able to get both significantly cheaper. Toyota Finance even reviewed Corey’s figures and confirmed they couldn’t beat them. I will never look to another finance company again.
Let us help with
unsecured business loans.
The details you want to know before taking the next step.
We're a finance broker: we compare 80+ banks and nonbank lenders and place your business loan with the best fit.
An unsecured loan generally leaves real estate outside the registered security and uses business performance for assessment. A director's guarantee may still apply.
Facility sizes depend on turnover and time in business, and many unsecured loans are funded within 48 hours of approval. We'll give you a realistic figure upfront.
Lenders mainly assess trading history, turnover and cash flow. We present those figures to lenders whose criteria fit the business.
Often, yes. Some lenders fund businesses with as little as six months trading. We match you to the ones comfortable with your stage and sector.
Usually, yes. Most unsecured business loans use a director's guarantee while your home stays outside the registered security. You stand behind the loan personally, and we explain that commitment before anything is signed.
It varies by lender. Some unsecured lenders collect small daily or weekly debits; others run standard monthly repayments. We match the frequency to your cashflow and show you the full repayment schedule before you commit.
Often, and many lenders discount the remaining interest when you do. Early payout terms differ between lenders, so if you might repay ahead of schedule, tell us upfront, we'll favour the lenders that reward it.
Frequently, yes. Some lenders on our panel will lend with a tax debt in the mix, and some will fund the payout itself, provided there's a plan around it. Talk to your accountant about the tax side; we'll arrange the lending side.
Common examples include working capital, stock, marketing, fit-out, tax obligations, business expansion. This is not a restricted list: the lender will still look at the exact item or purpose, the amount requested and your circumstances.
A lender may ask for business bank statements, BAS, management accounts, tax portal, contracts, purchase orders. You may not need everything on that list. X Lend confirms what applies before anything is submitted.
For unsecured business loans, we first confirm the transaction, timing and available evidence. We then explain the issues that matter, compare lenders whose rules fit those facts and show the proposed option before any application is submitted.
Reviewed by Corey Marino
FBAA member M-354085 · Diploma-qualified finance broker · Last reviewed 24 August 2026