

Truck Finance
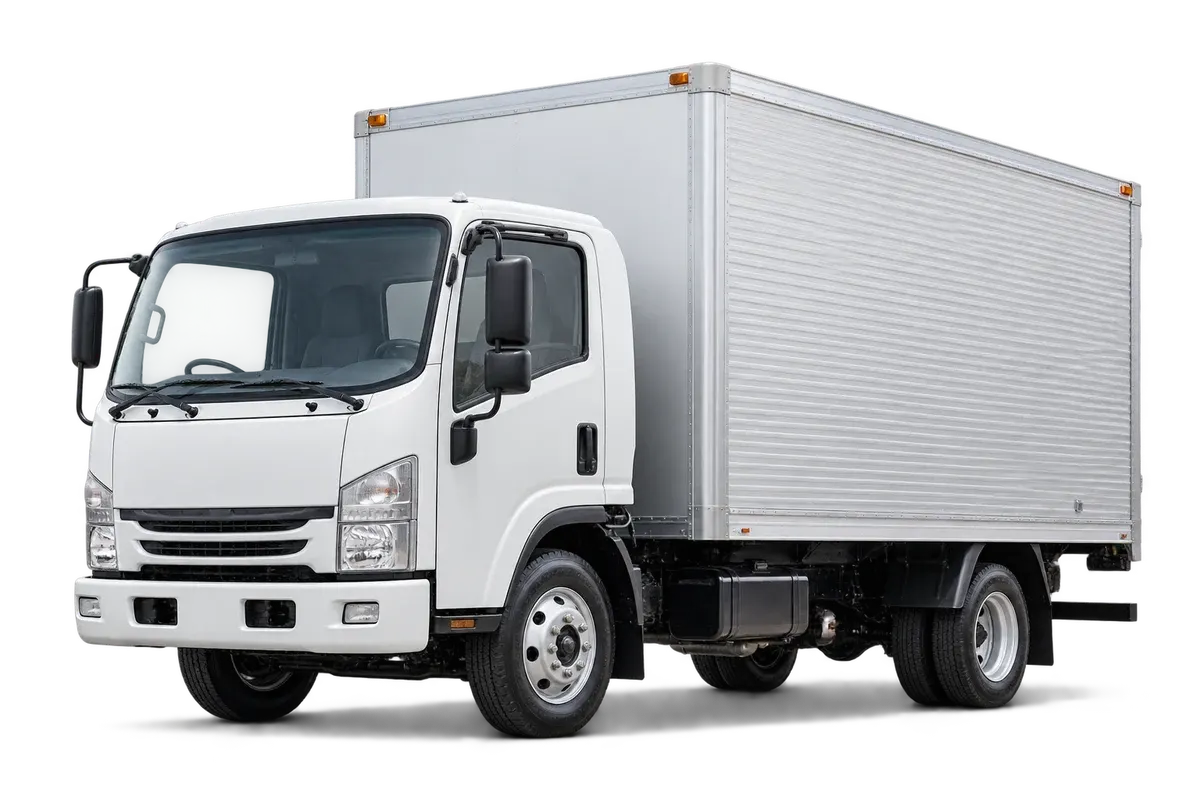
Prime movers, rigids, tippers and trailers, new or used, owner operator to fleet.
View finance optionsFund trucks, trailers and fleet upgrades with the route, operating costs and customer payment cycle in view.
A freight contract may pay after fuel, wages and registration are due. Compare the complete truck and trailer cost with the first operating period, including a slower start or a delayed invoice.
A truck loan funds an asset. Invoice finance may release cash against eligible completed work, while working capital covers a defined operating gap. Choosing the structure starts with when cash leaves and comes back.
X Lend compares suitable options from its panel of 80+ banks and specialist lenders. We explain the proposed rate, fees, repayment dates, security and any final balloon before you decide whether to authorise an application.
Choose the funding purpose first. Each option below explains the costs, evidence and next steps for that type of finance.
Prime movers, rigids, tippers and trailers, new or used, owner operator to fleet.
View finance options
Vans, light commercials and support vehicles for last mile and depot runs.
View finance options
Forklifts, trailers, GPS/telematics and depot equipment that keep freight flowing.
View finance optionsFund a defined gap between business costs and receipts, with a repayment plan linked to how that gap closes.
View finance optionsAccess funding against eligible unpaid business invoices. Compare debtor eligibility, fees, recourse and collection arrangements.
View finance optionsA term loan for a defined business purpose. Compare the total cost, director guarantees and any business security.
View finance optionsOne broker to compare our panel of 80+ banks and specialist lenders.
Talk through your optionsWe consider customer payment terms alongside fuel, tyres, wages, maintenance and the first loan debit.
Cab, chassis, body and trailer details help identify suitable asset policy and settlement requirements.
We check the available business and asset documents against lender requirements. Low doc means a different evidence pathway, not no assessment.
Compare the rate, fees, repayment dates, guarantees and any balloon together. Your accountant can confirm the tax treatment of the proposed structure.
We identify the outstanding conditions and supplier steps. Decision and settlement timing depend on the lender, documents and transaction.
Your broker coordinates the application, lender questions and settlement documents, keeping you informed about what is needed next.
The right finance should support the work ahead. Compare what it makes possible with the cost and commitment of borrowing.
Match cab, chassis, body and payload with the freight and contract before choosing finance.
Spreading an eligible truck purchase can preserve a buffer for fuel, wages, tyres and servicing.
Compare keeping an older vehicle with the repayment and operating costs of a replacement.
Confirm the route and any applicable access arrangements; finance approval does not establish road access.
Fuel and wages can fall due before customers pay. Include that gap in the repayment budget.
Compare term, fees, guarantees and final balloon alongside registration, maintenance and insurance costs.
NHVR distinguishes general access vehicles from vehicles that need access under a notice or permit. Registration alone does not establish access for every heavy vehicle combination or route.
NHVR: do I need an access permit?Before committing, confirm the body, payload, operating route and access arrangements with the appropriate authority. Budget for registration, insurance, servicing, tyres and fuel alongside the loan. Compare customer payment terms with weekly operating expenses, especially when adding a vehicle before a contract starts.
The source explains the operating context. Your broker checks the finance documents and lender requirements for your application.
Explore Heavy truck finance, Fleet finance, Forklift finance, Prime mover and trailer structures.
Get clear on eligibility, paperwork and the next steps before you apply.
Ask a brokerThere may be suitable lenders. We check the truck age, kilometres, condition, value and expected age at the end of the loan, alongside the business position and service history.
Yes. Your driving experience, contract, contribution and operating budget can help explain a newer business. We assess those together with current finances and lender requirements before a formal submission.
We can assess a fleet purchase alongside individual vehicle finance. Provide each vehicle quote, delivery date and existing payout, then test the combined repayments and running costs against the work available.
We compare suitable options from our accredited panel of 80+ banks and specialist lenders. The panel is not every lender in Australia, and the lender makes the credit decision.
An initial quote does not create a lender credit enquiry. With your written authority, we can access your personal credit report as an authorised access seeker without a lender enquiry or score impact. A formal lender application and credit enquiry only follow when you authorise them.
Standard applications range from $0 to $990 including GST. Applications requiring extended specialist work range from $991 to $1,990. Highly specialised applications requiring extensive consultation range from $1,990 to $2,500 and are very rare. These ranges include GST; your actual fee is quoted before you proceed. A broker fee is payable only if the finance settles. We may also receive lender commission ranging from 0% to 5% of the loan amount. Your separate written fee quote sets out your broker fee for acceptance before you proceed. Our Credit Guide explains commission, referral and volume bonus arrangements and how to request figures for your application.
$52,000 settled
Approved on the first lender enquiry and settled at a historical rate of 9.69%, allowing the new delivery run to begin on time.
Read case study
$310,000 settled
Approved on the first lender enquiry and settled at a historical rate of 9.59%, reducing the ongoing cost and moving the truck into proper business ownership. Not included in this anonymised summary: how the $30,000 deposit was applied to the refinance and the before-and-after total cost.
Read case study
$90,000 limit
Approved on the first lender enquiry and settled with a $90,000 limit and access to up to 85% of eligible invoices, allowing weekly payroll to continue without waiting for customers. Not included in this anonymised summary: the facility fees.
Read case study