
The right borrower and purpose
We align the application and invoice with who is buying the vehicle and its intended use.
Business vehicle finance for the car, ute or van your work needs. Compare ownership options, repayments and any final balloon before choosing your finance.

Business vehicle finance spreads the purchase cost of a work car, ute or van. X Lend checks the vehicle, business use and available records, then explains suitable finance and the proposed costs before you apply.
A ute for tools, site visits and trade work
A van for deliveries, stock or mobile services
A company car for directors or employees
An electric or hybrid work vehicle
A used or private sale vehicle
A replacement vehicle, fleet addition or existing loan refinance
Have something in mind? Let’s talk finance.
Get my free quoteTell us who will buy the vehicle, who will use it and how it will earn its place in the business. We check the proposed borrower, invoice, ownership and finance together. Your accountant can confirm the tax treatment of the arrangement you are considering. For a company or trust, confirm the exact applicant and anyone signing or guaranteeing the finance before the quote is issued. For mainly personal use, start with the Car Loans pathway and explain the actual use.
We align the application and invoice with who is buying the vehicle and its intended use.
Bring a bank or dealer offer to compare on the same amount, term, balloon and fee basis.
We coordinate documents, seller details and existing finance payouts around your delivery date.
A young ABN needs context beyond its registration date. Bring the work secured, your industry experience and the business records already available. Separate confirmed contracts from forecasts so we can assess the right evidence pathway.
Business.gov.au: buying or leasing vehicles and equipment · Business.gov.au: preparing a business loan
The ownership arrangement matters alongside the repayment. We explain available structures; your accountant confirms their tax treatment for your business and intended use.
Your business buys the vehicle and the lender takes security over it. Repayments run over the agreed term, with any balloon due at the end. Check early payout conditions if you expect to upgrade.
The financier owns the vehicle and you pay to use it. Check the residual and final obligations. Servicing and the right to hand the vehicle back are not automatically included.
You use the vehicle while paying instalments. Ownership transfers after the final payment and purchase conditions are met. Compare the full payment schedule with a secured loan where available.
| Your proposed purchase | What we need to establish | Useful evidence |
|---|---|---|
| Business buys the vehicle | Purchasing entity, intended use, ownership under the contract and any director guarantee. | Correctly addressed supplier quote, available trading records and current commitments. |
| You buy it for work | Personal ownership, actual work/private use and income supporting the repayments. | Personal and relevant business income records, commitments and the proposed vehicle invoice. |
| Vehicle has mixed use | Who pays, who owns and how the vehicle is used. The finance and accounting treatment need to fit those facts. | A clear use explanation and the business/personal records relevant to the proposed borrower; tax treatment confirmed with the accountant. |
| Business is still young | Continuity of work and experience, existing income and the difference between secured work and forecasts. | Available BAS, banking, contracts and prior industry experience. No universal minimum ABN age implied. |
In a hypothetical $50,000 purchase, a $25,000 trade-in with an $18,000 payout contributes $7,000. Add a $3,000 cash deposit and the requested vehicle funding is $40,000 before financed fees.
If the payout is $28,000 instead, the $25,000 trade-in has a $3,000 shortfall. Identify how that shortfall will be cleared; do not count it as a deposit or assume it can be added to the new loan.
Compare the net amount, financed fees, term, total repayable and any final balloon together. Check early-payout terms if you expect to upgrade before the loan ends. Check that quotes use the same GST basis and confirm the actual amount financed.
A balloon keeps part of the loan outstanding until the end and can increase total interest compared with repaying that amount during the term. Consider expected kilometres, replacement timing and cash available at the finish. The vehicle's future sale price and a future refinance are not certain ways to clear it.
Let’s compare your options.
Get my free quoteTry the amount you need after your deposit or trade-in, then compare different terms and balloon amounts.
Adjust the amount, term and rate to see an indicative repayment.
Illustration only, not a lender offer. Starts at 6.95% p.a. over five years, with any optional balloon at 0%. Assumes $1,490 in upfront fees financed and $0 ongoing fees. These are modelling assumptions, not actual X Lend or lender charges. Total repayable counts fees and any final balloon once. Weekly and fortnightly figures are monthly-payment equivalents.
The calculator models your inputs. Its starting rate is not a quote, and the estimate does not include every fee or tax effect or assess lender eligibility.
Check the proposed repayment frequency, total payments and balloon. Allow separately for fuel, servicing, registration, insurance and repairs, especially for a heavily used vehicle.
Find my optionsWe look at the business and the purchase together. A well-established business buying a familiar work vehicle can need different evidence from a new operator buying their first van.
Low doc options may use other evidence, but low doc does not mean no assessment. ABN history, credit conduct, the vehicle and requested amount influence what a lender needs. We check the available pathway before asking for documents you may not need.
Bring your previous industry experience, current work, contracts and available business records. These help explain how the vehicle will be used and repaid. We separate work already secured from forecast income and check lender appetite before making a formal application.
Strong turnover can still leave little room for another repayment after existing loans, wages and operating costs. Lenders assess that repayment capacity alongside the vehicle's value and expected use, which can affect the available term and amount.
The contractor had not reached 12 months in business and did not have a complete financial year of tax returns, but needed the ute before a new contract began.
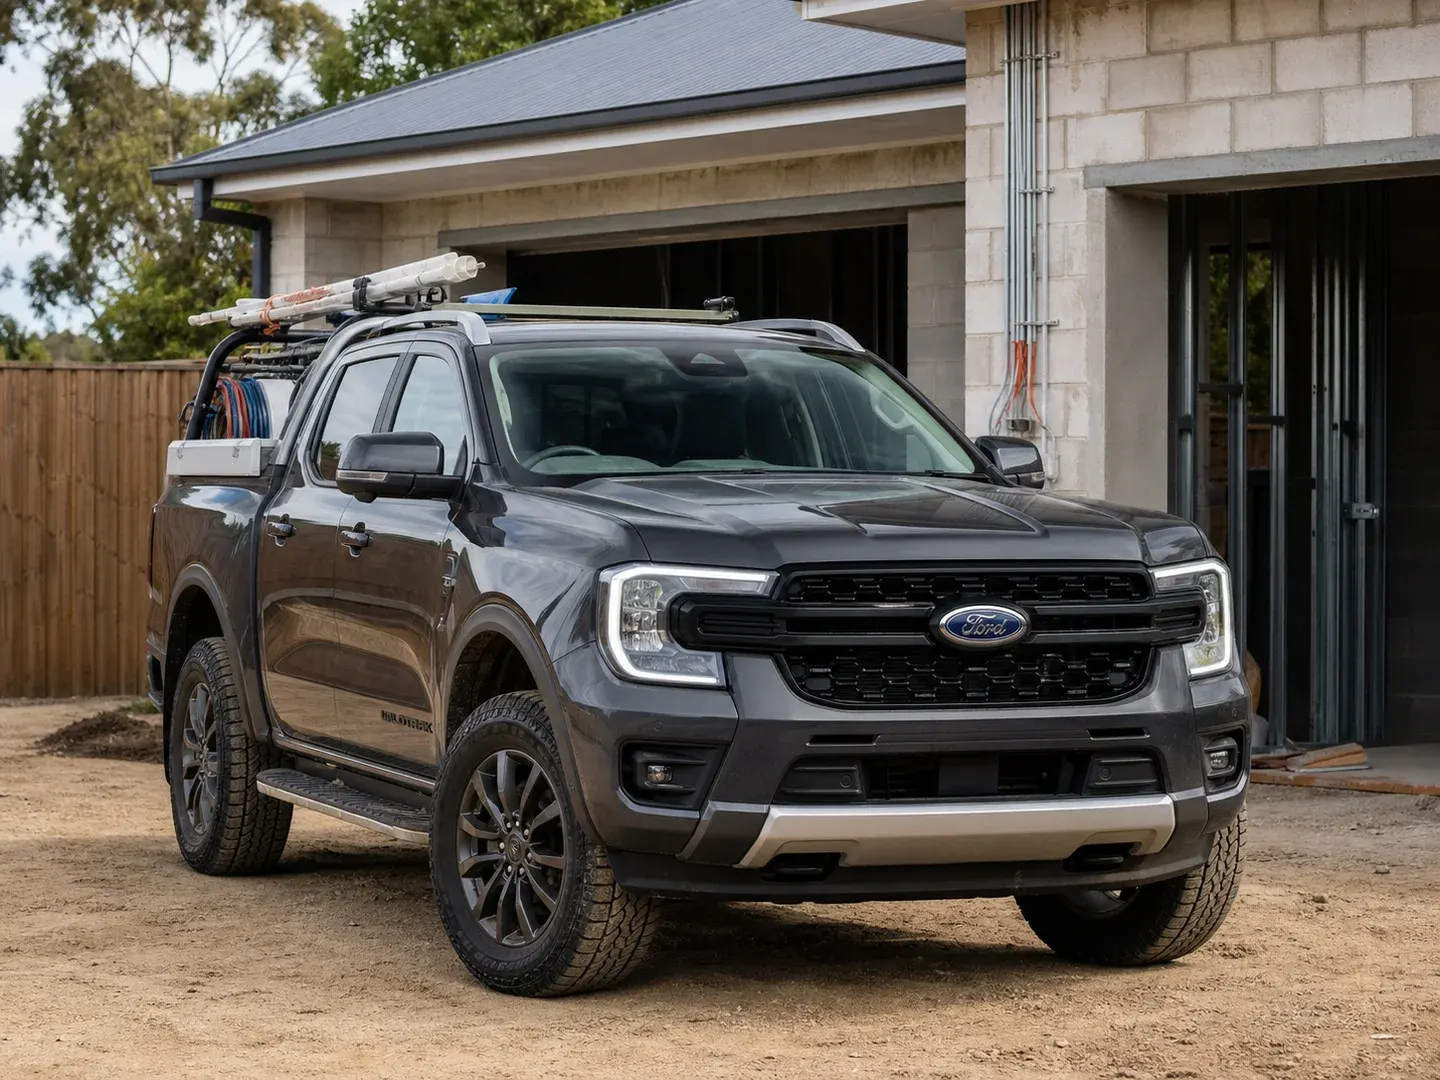 Business ute finance · Penrith, NSW
Approved on the first lender enquiry and settled for the full amount at a historical rate of 9.4%, with no deposit, before the new contract started.
Historical customer outcome. Vehicle and business images are illustrative.
Find out what’s possible for you.
Get my free quoteStart with the purchase details. We work through the lender fit and proposed terms before you decide whether to apply.
Share the quote or listing, intended use, purchasing entity and timing. Tell us about any trade-in or existing finance.
We assess the proposed borrower, vehicle and business evidence, then explain the proposed rate, fees, repayments, balloon, security and any lender or director-check requirements before an application.
You choose whether to proceed. With your consent, we prepare the selected lender application and explain the credit enquiry and remaining approval conditions.
We work through signed documents, insurance requirements and any payout with the lender and seller, then confirm settlement arrangements for handover.
Tell us what you need and where things stand. We explain suitable options and the proposed costs before you choose whether to apply.
Finance is our core service. We do not routinely promote insurance or warranties. We only assist with these when a customer specifically asks. How we work.
Choose the option that supports the work while leaving the business enough breathing room.
Replace an unreliable vehicle without using all your operating cash.
Spread a purchase cost across the years you expect to use the vehicle.
Add capacity for existing work while retaining funds for wages and stock.
Cash avoids finance charges if the business can spare it comfortably.
Hiring may suit a temporary contract without a long ownership commitment.
Keeping the current vehicle may cost less if it remains reliable and fit for the job.
I had a great experience working with Corey and couldn’t recommend him highly enough. He went above and beyond to help me throughout the process, providing valuable guidance and advice on how to improve my chances of approval. Corey is extremely knowledgeable, experienced, efficient and his communication was excellent from start to finish. He kept me informed at every stage, always approachable and was never difficult to get in touch with whenever I had questions.
I had a great experience dealing with Corey and the finance team. Corey was professional, friendly, and extremely helpful throughout the entire process. He made everything straightforward, communicated clearly, and went above and beyond to make sure everything went smoothly. His knowledge, efficiency, and excellent customer service made the whole experience stress-free. I highly recommend Corey and the team to anyone looking for reliable and professional finance services. Thank you, Corey, for your outstanding service!
Really happy with the service I received from Corey. Before speaking with Corey, I’d already been knocked back by THREE other places and was honestly starting to think getting finance wasn’t going to happen!! Corey took the time to understand my situation and actually put in the effort to help me out. He was easy to deal with, kept me updated throughout the whole process and was always happy to answer any questions I had. What I appreciated most was that he didn’t just brush me off like the others. He genuinely went out of his way to help and made the whole process a lot less stressful. Couldn’t recommend Corey enough. Thanks again mate, really appreciate everything you’ve done for me and making my dream come true!
Let us help with
business vehicle finance.
The details you want to know before taking the next step.
Yes, with a lender that accepts the transaction. We confirm seller and vehicle details, arrange the relevant checks and coordinate any finance payout. A PPSR search shows registered security interests; it does not establish ownership or replace a mechanical inspection.
It may be included when the lender accepts the accessories and completed vehicle value. Provide separate prices for the vehicle, canopy, shelving or other equipment, especially if different suppliers and delivery dates are involved.
Business vehicle finance can use the vehicle itself as security. A director guarantee can still make you personally responsible if the business cannot pay, even where no home mortgage is given. We explain the guarantee and any additional security requested by the selected lender. Check what the actual documents cover before you sign.
We assess the payout, remaining term and vehicle value. Compare the existing loan's remaining cost with switching fees and the new payment schedule. Lower repayments achieved by extending the term can increase total cost.
No. Green vehicle pricing depends on the vehicle and lender. We compare any eligible offer with standard finance using the same term and balloon, including fees, to see which costs less.
Start early. We check whether an approval can cover the delivery date and what needs updating later. Confirm deposit and contract conditions before committing to an order that depends on finance.
No. With your written authority, we can obtain your personal credit report as an authorised access seeker. This records file access rather than a credit application enquiry and does not affect your score. A formal lender application and credit enquiry only follow once you authorise them.
Equifax: soft and hard credit checks · OAIC: credit reporting terms

Reviewed by Corey Marino
FBAA member M-354085 · Diploma-qualified finance broker · Last reviewed 25 October 2026 · Content updated