

Equipment Finance
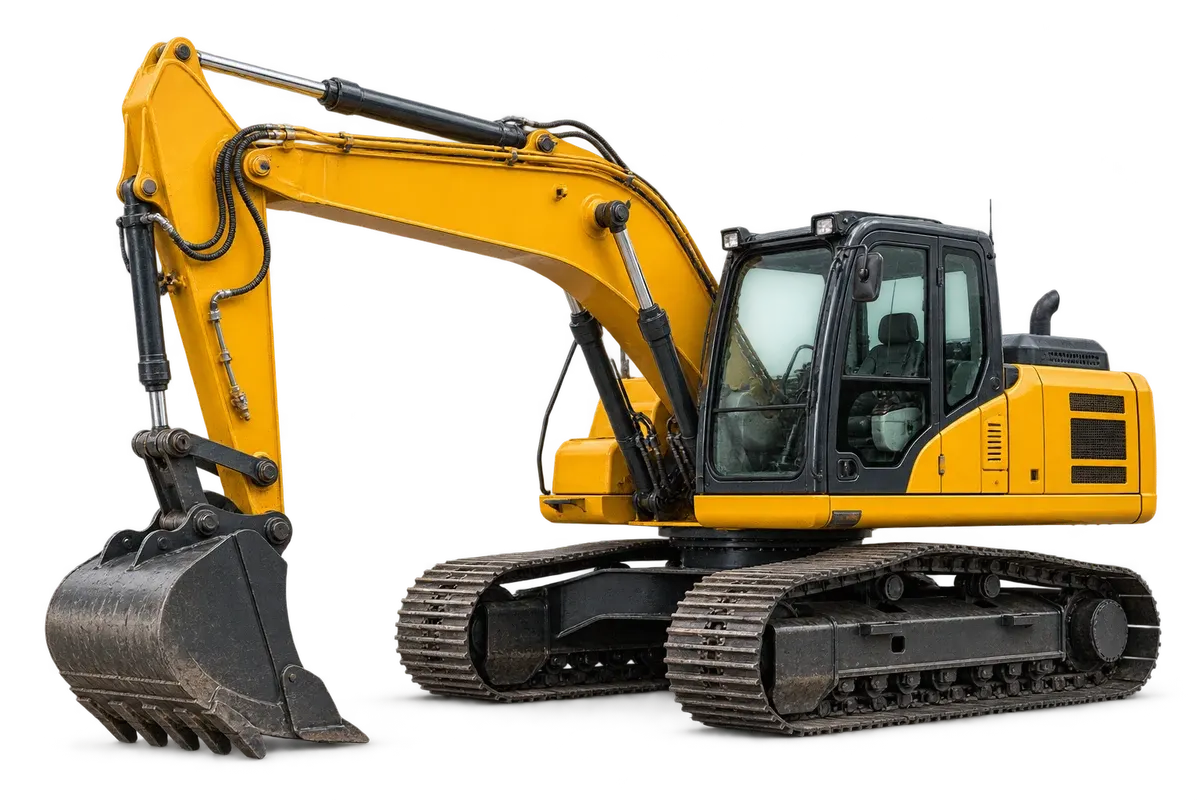
Excavators, dozers, loaders, rollers and attachments, the plant that wins and delivers the job.
View finance optionsFinance excavators, loaders and civil plant around the machine, the contract and the cash it can earn.
Machine hours, attachments, mobilisation and repair exposure matter as much as the sticker price. Start with the work the asset will perform, the expected utilisation and the full cost of getting it on site.
Keep the plant purchase separate from float transport, fuel, labour and the gap before a principal pays. Asset finance can spread the machine cost; a working capital facility addresses a different timing need.
X Lend compares suitable options from its panel of 80+ banks and specialist lenders. We explain the proposed rate, fees, repayment dates, security and any final balloon before you decide whether to authorise an application.
Choose the funding purpose first. Each option below explains the costs, evidence and next steps for that type of finance.
Excavators, dozers, loaders, rollers and attachments, the plant that wins and delivers the job.
View finance options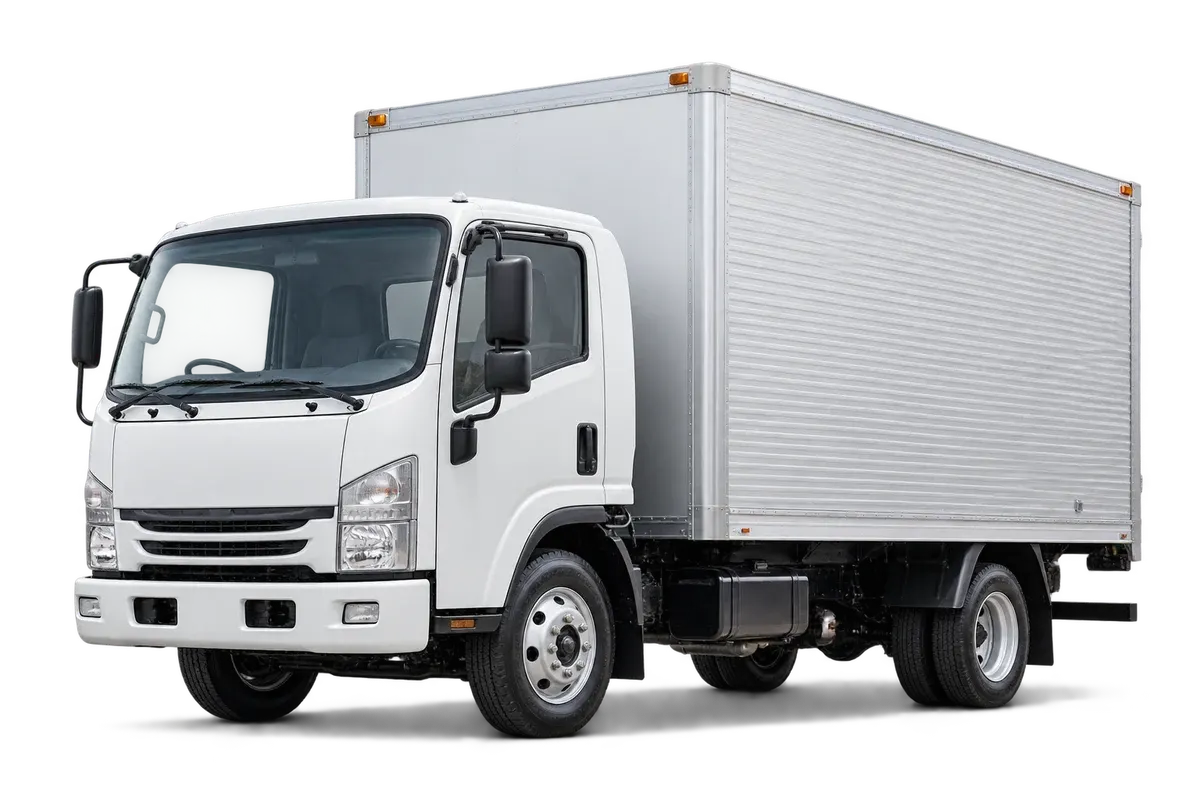
Tippers, floats, water carts and prime movers to move material and shift your machines between sites.
View finance options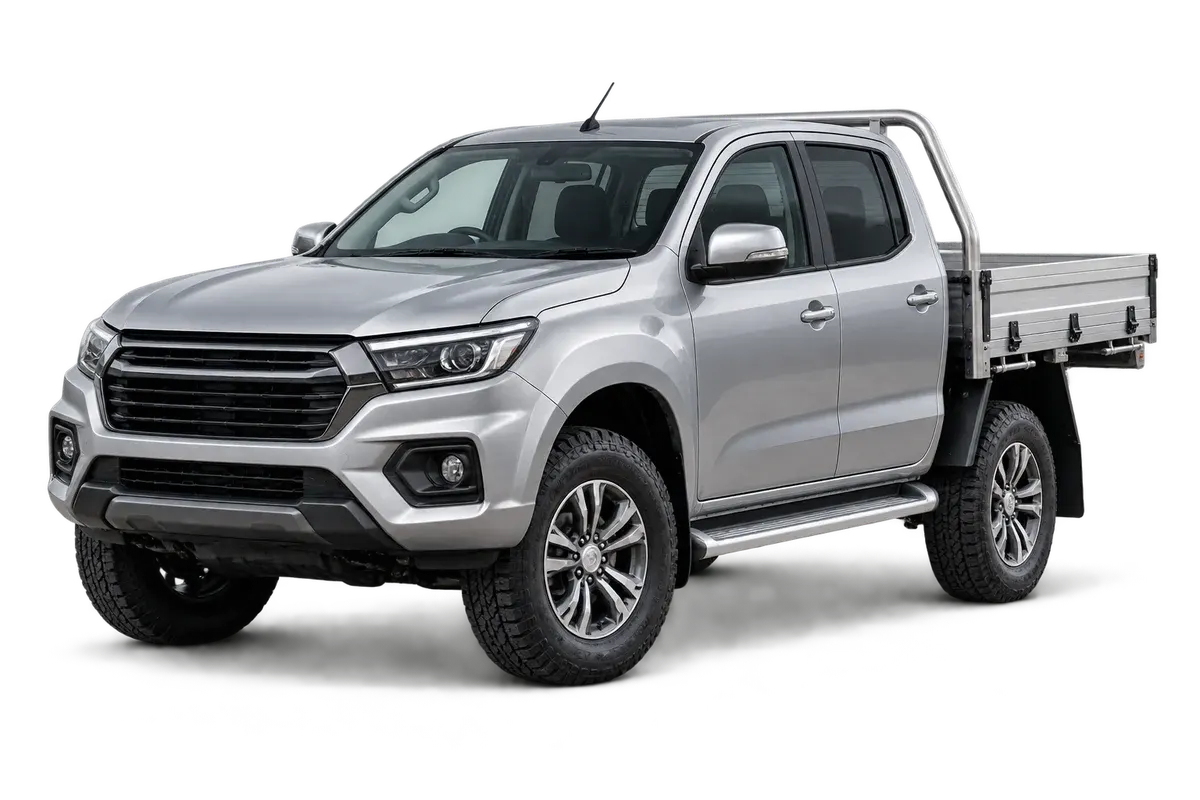
Utes, crew cabs and site vehicles to get the team and tools where the work is.
View finance optionsA term loan for a defined business purpose. Compare the total cost, director guarantees and any business security.
View finance optionsFund a defined gap between business costs and receipts, with a repayment plan linked to how that gap closes.
View finance optionsA reusable facility for recurring cash gaps. Check interest on drawn funds, fees and review conditions.
View finance optionsOne broker to compare our panel of 80+ banks and specialist lenders.
Talk through your optionsCompare booked hours, downtime and payment terms with repayments. A projected full workload is different from contracted work.
We put the machine details and supporting quote together so the lender can assess the actual asset being purchased.
We check the available business and asset documents against lender requirements. Low doc means a different evidence pathway, not no assessment.
Compare the rate, fees, repayment dates, guarantees and any balloon together. Your accountant can confirm the tax treatment of the proposed structure.
We identify the outstanding conditions and supplier steps. Decision and settlement timing depend on the lender, documents and transaction.
Your broker coordinates the application, lender questions and settlement documents, keeping you informed about what is needed next.
The right finance should support the work ahead. Compare what it makes possible with the cost and commitment of borrowing.
Compare the machine and attachments with the site, contract and work you expect it to perform.
Spreading an eligible machine purchase can leave cash available for transport, fuel and getting established on site.
Compare repairs and hire costs with the full cost of buying a reliable replacement.
Used machine hours, service records and likely repairs matter as much as the advertised purchase price.
Test repayments during wet weather, site delays or low utilisation while fixed expenses continue.
Include the required attachments, float transport and site setup, then compare fees, total repayments and any balloon.
The national plant model code addresses inspection, maintenance and the specific risks of powered mobile plant. Used equipment needs attention to its condition and available operating information.
Safe Work Australia: managing plant risks (November 2024)Compare machine hours, service history, attachments, float transport and site mobilisation before settling on the amount. Model a quieter utilisation period as well as a full workload. A low monthly payment can still be expensive if the machine spends weeks idle or needs major repairs.
The source explains the operating context. Your broker checks the finance documents and lender requirements for your application.
Explore Excavator finance, Small truck finance, Asset age and finance terms.
Get clear on eligibility, paperwork and the next steps before you apply.
Ask a brokerWe assess the exact machine and seller. Lender fit depends on age, hours, condition, value, ownership evidence and the proposed term. Supply the serial number, service history and attachments with the quote.
The contract can explain the purpose and projected receipts. We also consider mobilisation costs, payment conditions, existing debt and the business evidence available before choosing a lender pathway.
List those costs separately. The lender decides which purchase costs can be financed. Fuel, wages and a payment gap may call for a different facility with a repayment period that fits the job.
We compare suitable options from our accredited panel of 80+ banks and specialist lenders. The panel is not every lender in Australia, and the lender makes the credit decision.
An initial quote does not create a lender credit enquiry. With your written authority, we can access your personal credit report as an authorised access seeker without a lender enquiry or score impact. A formal lender application and credit enquiry only follow when you authorise them.
Standard applications range from $0 to $990 including GST. Applications requiring extended specialist work range from $991 to $1,990. Highly specialised applications requiring extensive consultation range from $1,990 to $2,500 and are very rare. These ranges include GST; your actual fee is quoted before you proceed. A broker fee is payable only if the finance settles. We may also receive lender commission ranging from 0% to 5% of the loan amount. Your separate written fee quote sets out your broker fee for acceptance before you proceed. Our Credit Guide explains commission, referral and volume bonus arrangements and how to request figures for your application.
$96,000 settled
Approved on the first lender enquiry and settled at a historical rate of 10.89%. The private seller was paid through the verified process and the business brought the tipper work in-house.
Read case study
$65,000 settled
Approved on the first lender enquiry and settled at a historical rate of 9.95%, quickly enough to keep the active project running.
Read case study