Directors' Vehicle Finance
Partner and staff vehicles, novated or chattel mortgage, structured for the firm.
View finance optionsVehicles, fitouts and cashflow for accountants, consultants and agencies, we compare 80+ lenders so growth never gets stuck waiting on receivables.
Google reviewsRead client feedback

Accountants, consultants, agencies and advisory firms don't carry heavy machinery, their costs are people, premises, technology and the gap between doing the work and getting paid. X Lend is a finance broker: we compare a panel of 80+ banks and nonbank lenders and arrange the finance so a growth push or a slow debtor month never stalls the business.
Because professional firms are asset light, they're often well regarded by lenders for unsecured and cashflow facilities, but the right structure matters. We match your firm to lenders who price recurring revenue and strong receivables well, with low doc options for established ABNs.
Whether it's a fitout for a bigger office, vehicles for partners and staff, new technology, or working capital to bridge billing cycles, we structure the finance around your cashflow and handle the lender so you can focus on clients.
The vehicles, premises and working capital behind a growing practice:
Partner and staff vehicles, novated or chattel mortgage, structured for the firm.
View finance optionsFund an office fitout, a hire or a growth push without putting up property.
View finance optionsSmooth payroll and overheads between billing cycles and slow paying clients.
View finance optionsRelease cash tied up in unpaid fees so growth doesn't outrun working capital.
View finance options
IT, AV, servers and office technology that keep the team productive.
View finance optionsBuying a competitor, a fee base or a book of clients? Fund the deal and the goodwill.
View finance optionsOne broker to compare our panel of 80+ banks and specialist lenders.
Talk through your optionsWe compare the market in one go to find the best fit and rate for an asset light firm.
Professional firms often access strong unsecured and cashflow facilities, we know who prices them keenly.
Invoice and cashflow finance turn unpaid fees into working capital without new property security.
Trading history can stand in for the full pack, keeping approvals fast.
Novated, chattel mortgage or lease for partner and staff cars, aligned to your position.
You focus on clients; we manage the lender, paperwork and settlement.
The right finance should support the work ahead. Compare what it makes possible with the cost and commitment of borrowing.
Access vehicles and equipment for new contracts, replacements or a growing workload.
Spread an eligible purchase over time while keeping a buffer for wages, materials and operating costs.
Replace unreliable assets when the cost of repairs and lost working time starts adding up.
Compare interest, fees and any final balloon payment alongside the total amount you will repay.
Repayments continue when work slows or customers pay late. Check the commitment against your cashflow.
Weigh repair costs and missed work against the cost of finance. Paying cash also reduces your available buffer.
business.gov.au's cashflow guidance covers records, payment terms, forecasting and managing costs. Profit and available cash can differ when invoices are still unpaid.
business.gov.au: guide to managing cash flowFor a practice expansion, separate one-off equipment and fit-out costs from ongoing salaries, subscriptions and rent. Map progress billing and debtor collection against those commitments. Test how a late major invoice would affect the proposed loan or credit facility.
Source checked 5 September 2026. These planning points explain how to prepare; lender requirements and regulatory obligations depend on your circumstances.
Get clear on eligibility, paperwork and the next steps before you apply.
Ask a brokerWe're a finance broker: we compare a panel of 80+ banks and nonbank lenders and arrange the finance that best fits your firm.
Yes. Professional firms are often well suited to unsecured and cashflow facilities priced on revenue and receivables rather than hard assets. We match you to lenders comfortable with asset light businesses.
That's exactly what cashflow and invoice finance do. We can release the cash tied up in unpaid fees, or set up a facility that smooths payroll between billing cycles.
Yes. Fitouts are commonly funded via an unsecured business loan, and IT/AV via equipment finance, both keep your cash free for hiring and growth.
An indicative quote doesn't touch your credit file. A formal application involves a credit check, but we only lodge once you're happy to proceed.
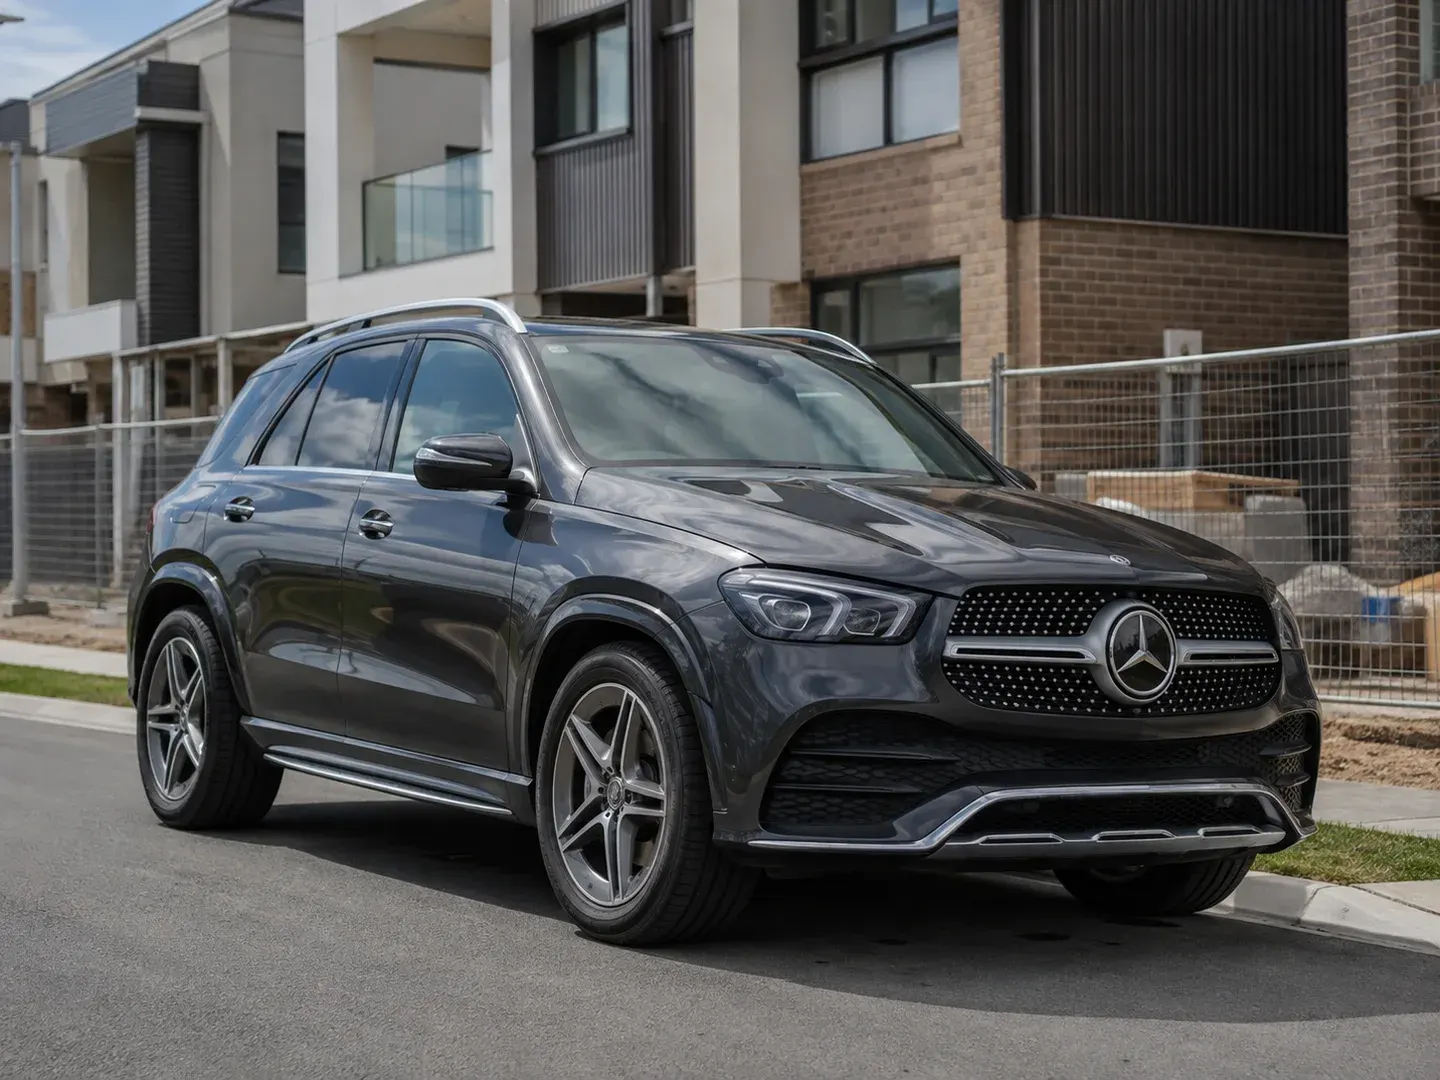
$118,000 settled
Approved on the first lender enquiry and settled at a historical rate of 7.59%, with a 30% balloon used to manage the scheduled monthly repayment.
Read case study