80+ lenders, one application
We compare the panel in one go and match your bike to the lender most comfortable funding it, at a sharp rate.
Find your next ride. Your broker compares suitable bike finance from our 80+ lender panel and helps organise the application through to settlement.

Two wheels or three, commuter or collector, we arrange finance for:
Road and naked bikes
Cruisers and tourers
Adventure and dual sport bikes
Learner approved (LAMS) bikes
Scooters and mopeds
Dealer and private sale purchases
New and used machines
Refinancing an existing bike loan
These motorbike examples are not a restricted list. Age, condition, value and suitability as loan security generally matter more than the badge.
The motorbike finance process and paperwork change depending on whether the motorbike comes from a dealer, private seller or an existing loan being refinanced.
These records help confirm income, identify the motorbike and reconcile the amount that must be paid at settlement.
Have something in mind? Let’s talk finance.
Get my free quoteWhether it's a daily commuter that skips the traffic or a weekend machine for the twisties, the finance shouldn't be the hard part. X Lend is a finance broker: we take one application and compare it across 80+ banks and nonbank lenders to find a rate that suits your profile.
We compare the panel in one go and match your bike to the lender most comfortable funding it, at a sharp rate.
Dealer floor or a private buy online, we arrange finance either way and handle the seller checks.
From a first LAMS approved commuter to a big adventure tourer, there's a lender for your ride.
New or used, dealer or private sale, learner legal or litre class, we arrange the finance around the bike you want. Preapproval gives you a clear plan before you buy and can help the purchase move sooner.
We compare your situation across the panel and explain realistic pathways in plain English before any application. We submit only after you choose to proceed, and an initial quote leaves your credit file untouched.
Many bike applications get a decision the same day, with settlement often inside 24 hours once approved.
Know your budget and negotiate like a cash buyer, with finance ready to settle.
Comparison rates shown upfront, terms to suit your budget, and no early exit traps.
From a first LAMS approved commuter to a litre class tourer, there's a lender on our panel for the ride, and with many bike loans decided the same day and settled inside 24 hours, you could be riding within the week.
Try an amount and term for your motorbike finance. When you’re ready, we’ll compare the options available to you.
Adjust the amount, term and rate to see an indicative repayment.
Estimate only. Calculations include an assumed $990 broker origination fee and $500 lender fee, both financed. Total repayable includes those fees, interest and any final balloon. Weekly and fortnightly figures are equivalents of the monthly estimate. Actual fees and repayment timing depend on your offer.
Your quote takes your circumstances and finance requirements into account. Compare your rate, fees and repayments together before choosing an offer.
Find my optionsThe customer's income appeared low under a standard assessment, even though the employer paid for accommodation, food and fuel.
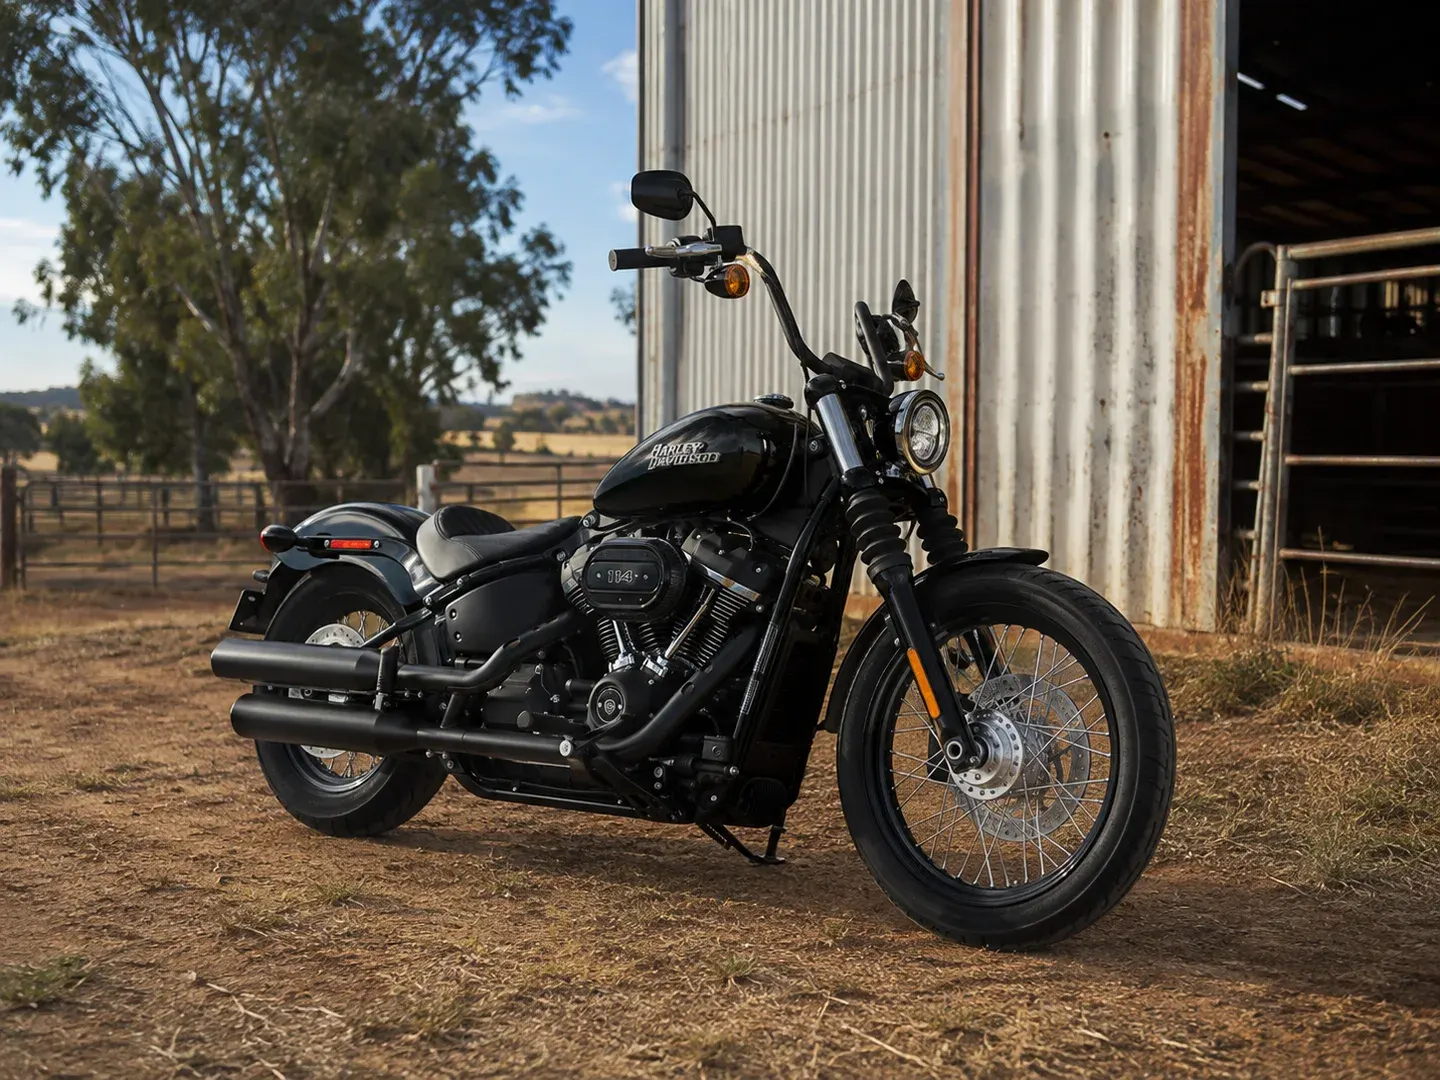 Motorbike finance · Regional NSW
Approved on the first lender enquiry and settled for the full amount at a historical rate of 10.4%, with no deposit.
Historical customer outcome. Vehicle and business images are illustrative.
Find out what’s possible for you.
Get my free quoteWe match your circumstances to suitable lenders for motorbike finance. Your broker helps you prepare the application.
For motorbike finance, a lender assesses the specific motorbike, the purchase or refinance transaction and whether the proposed repayments fit the applicant's verified budget. The sections below show how those checks connect.
Your broker handles the lender comparison and paperwork for motorbike finance, keeping you informed at each step.
Tell us what you want to finance, how much you need and when you need it. That could include road and naked bikes.
We help organise dealer invoice or sale agreement and VIN and check the lender criteria that apply to your circumstances to find lenders that fit your situation.
We explain the available rate, term, repayment and security options, including the full cost and how repayments fit your budget. You choose the option to take forward.
Your broker coordinates lender conditions, signed documents and payment details, so you can focus on what comes next.
Your broker reviews your enquiry and explains the next steps, usually within one business day. An enquiry does not create a credit check or an obligation to proceed.
Compare the ways you can arrange motorbike finance, with a broker to explain your options.
Swipe across the table to compare all columns.
| Option | During the loan | At the end |
|---|---|---|
| No balloon | Higher regular repayments than the same loan with a balloon; the balance reduces faster | The scheduled loan balance is repaid when all payments have been made. |
| A balloon payment | Lower regular repayments, but interest is charged on a larger outstanding balance | A lump sum remains due. Budget for it rather than assuming resale or refinancing will cover it. |
| A shorter term | Higher regular repayments may reduce total interest on otherwise equal terms | Check affordability alongside the total amount repaid, fees and any payout costs. |
Use the calculator to compare the same amount, rate and term with and without a balloon. Refinancing requires a new assessment and is not guaranteed.
The purchase price is only the starting point. Protective equipment, registration, insurance, servicing and any accessories should be considered before choosing the loan amount and term.
Road bikes, off-road bikes, scooters and ATVs may sit under different lender policies, particularly when they cannot be registered for road use.
Exhausts, luggage, riding gear and other accessories may not all be treated as part of the secured asset.
VIN, seller, payout and PPSR checks should be completed before funds are released.
Avoid setting a loan term that is likely to outlast how long you plan to keep the bike.
Motorcycle age, engine capacity, use, condition and model demand influence rules for using the asset as security. Accessories and riding gear may require itemisation on the invoice. In practice, those details can change the available lenders, the deposit required and the longest loan term offered.
For motorbike finance, a balloon leaves part of the amount as a lump sum due at the end. It can reduce regular repayments, but the final amount must still be paid or refinanced, so we compare both the repayment effect and total cost.
A dealer invoice usually puts the motorbike and seller details in one place. A private sale adds seller, ownership and Personal Property Securities Register checks; a refinance instead needs a current payout letter showing the existing balance.
The motorbike finance assessment then reconciles price, deposit, trade-in and any current payout with verified income, living costs and other debts to test whether the proposed repayment fits.
Illustrative examples of how we approach motorbike finance.
The buyer has found a suitable vehicle through a private seller and needs a secure settlement process.
We confirm the seller, vehicle, PPSR status and payout position, then coordinate lender payment instructions with both parties.
Seller identification, registration details, VIN, purchase agreement, payout letter where relevant and the buyer's income documents.
The applicant has moved into a new role with stable current income and a limited history in that position.
We review the employment type, probation terms and continuity of occupation, then compare lenders whose employment policy fits the verified position.
Employment contract, recent payslips, bank credits and evidence of prior work in the same field.
Older credit events appear on the file while recent banking conduct and income show a stronger current position.
We explain the event, confirm its status and present the current income and expense evidence to lenders that assess the complete credit story.
Credit report, proof of payment or release, recent bank statements, payslips and a written explanation of the circumstances.
At X Lend, we first make the purchase amount, purpose and comfortable repayment clear. We then compare suitable panel options on the same term and fee basis, explain the total cost and ask the customer to approve the selected lender submission.
Let’s compare your options.
Get my free quoteSee how arranging finance compares with waiting or paying the full cost upfront.
Access a suitable motorbike without waiting to save the full purchase price.
Keep more savings available for emergencies after arranging the motorbike.
Replace an unreliable or unsuitable motorbike before downtime and repair costs increase.
Work, family commitments or travel can remain disrupted without a reliable motorbike.
An older motorbike can keep creating downtime or repair costs while its replacement is delayed.
Paying the full motorbike purchase price from savings can leave less buffer for unexpected expenses.
Corey was excellent to deal with. He was able to get me a better rate than everyone else, he was very responsive, worked quickly and made the process very easy, even with me asking a million questions. I would definitely use him again next time.
I can’t recommend Corey from X Lend highly enough. From the very first conversation, he was professional, transparent, and genuinely focused on finding the best outcome for me. Corey took the time to explain every step of the finance process in a way that was easy to understand, answered all my questions promptly, and never once made me feel rushed or pressured. I really appreciated how proactive he was, keeping me updated, following up with lenders, and making sure everything stayed on track. What really stood out was how hard he worked to secure a great deal. He compared multiple lenders, negotiated on my behalf, and ultimately achieved a rate and repayment structure that exceeded my expectations. The whole process of purchasing my car was smooth and stress‑free thanks to their expertise. If you’re looking for someone knowledgeable, reliable, and genuinely in your corner, I wouldn’t hesitate to recommend them. I’ll definitely be using their services again in the future :)
Corey helped me through the entire process of getting my dream family car! He was extremely prompt with his responses and had everything organised quickly and smoothly. I made a huge mistake by settling finance on the wrong car (a 5‑seater instead of a 7‑seater), but Corey was incredibly understanding and supportive. He contacted the dealership, lender, and even rearranged my insurance for me. He did all of this without ever making me feel like a hassle, even though I knew I was being a pain! Despite the setback, Corey stayed fast and efficient, kept me confident throughout the process, and managed to get everything cancelled and re‑approved for a higher amount so I could get my actual dream car. I highly recommend Corey. He speaks to you like a friend and genuinely has your best interests at heart. I already had quotes from Toyota Finance and Toyota Insurance, and Corey was able to get both significantly cheaper. Toyota Finance even reviewed Corey’s figures and confirmed they couldn’t beat them. I will never look to another finance company again.
Let us help with
motorbike finance.
The details you want to know before taking the next step.
We're a finance broker. We compare 80+ banks and nonbank lenders and place your motorbike loan with the one offering the best fit and rate.
Absolutely. We arrange finance for everything from a first LAMS commuter to a big tourer once you're off your restrictions, matched to a lender comfortable with the bike and your situation.
Yes. Many of our lenders fund private sales as well as dealership purchases. We verify the bike and that it's clear of existing finance, then settle with the seller.
No. An indicative quote doesn't touch your credit file. We only run a formal credit check once you're ready to proceed with a lender.
Many motorbike loans get a same day decision and can settle within 24 hours of approval, often quick enough to ride away the same week.
Common examples include Honda CBR and CRF, Yamaha MT and YZF, Kawasaki Ninja and KLR, Suzuki GSX and V-Strom, Harley-Davidson, Ducati. This is not a restricted list: the lender will still look at the exact item or purpose, the amount requested and your circumstances.
A lender may ask for dealer invoice or sale agreement, VIN, registration, PPSR result, licence, payslips. You may not need everything on that list. X Lend confirms what applies before anything is submitted.
For motorbike finance, we first confirm the transaction, timing and available evidence. We then explain the issues that matter, compare lenders whose rules fit those facts and show the proposed option before any application is submitted.
Reviewed by Corey Marino
FBAA member M-354085 · Diploma-qualified finance broker · Last reviewed 24 August 2026