
Business Cashflow & Loan Coverage
Estimate the monthly buffer and simple debt coverage after adding a proposed business loan.
- Free to use with no signup
- No impact on your credit score
- Clear estimates you can adjust

Reviewed by Corey Marino Founder & Finance Broker, FBAA member M-354085 · Diploma-qualified finance broker
Last reviewed 25 October 2026 · About Corey
Exclude all loan repayments from this figure.
Monthly cashflow after proposed loan
Unavailable
- Cashflow before proposed loan
- Unavailable
- Proposed monthly repayment
- Unavailable
- Indicative debt-service coverage
- Unavailable
A positive buffer or coverage ratio is not an approval result. Lenders assess verified income, expenses, liabilities, conduct and their own serviceability rules.
Important information
Planning guide only, not an approval, credit assessment, accounting calculation or advice. Use verified figures and allow for seasonal and unexpected costs.
Detailed assumptions and limitations
- Revenue and operating expenses are monthly averages and assumed to remain stable through the proposed loan term.
- Operating expenses exclude debt repayments; existing and proposed debt are entered separately.
- The proposed loan uses level principal-and-interest repayments plus the entered monthly fee.
- Tax, drawings, working-capital swings, seasonal variation, balloon payments and lender serviceability adjustments are excluded.
FAQ
Can the business carry another repayment?
Use a realistic average and then stress-test slower months before borrowing.
Explore cashflow finance, lines of credit and unsecured business loans.
Genuine settled outcomes
Related case studies
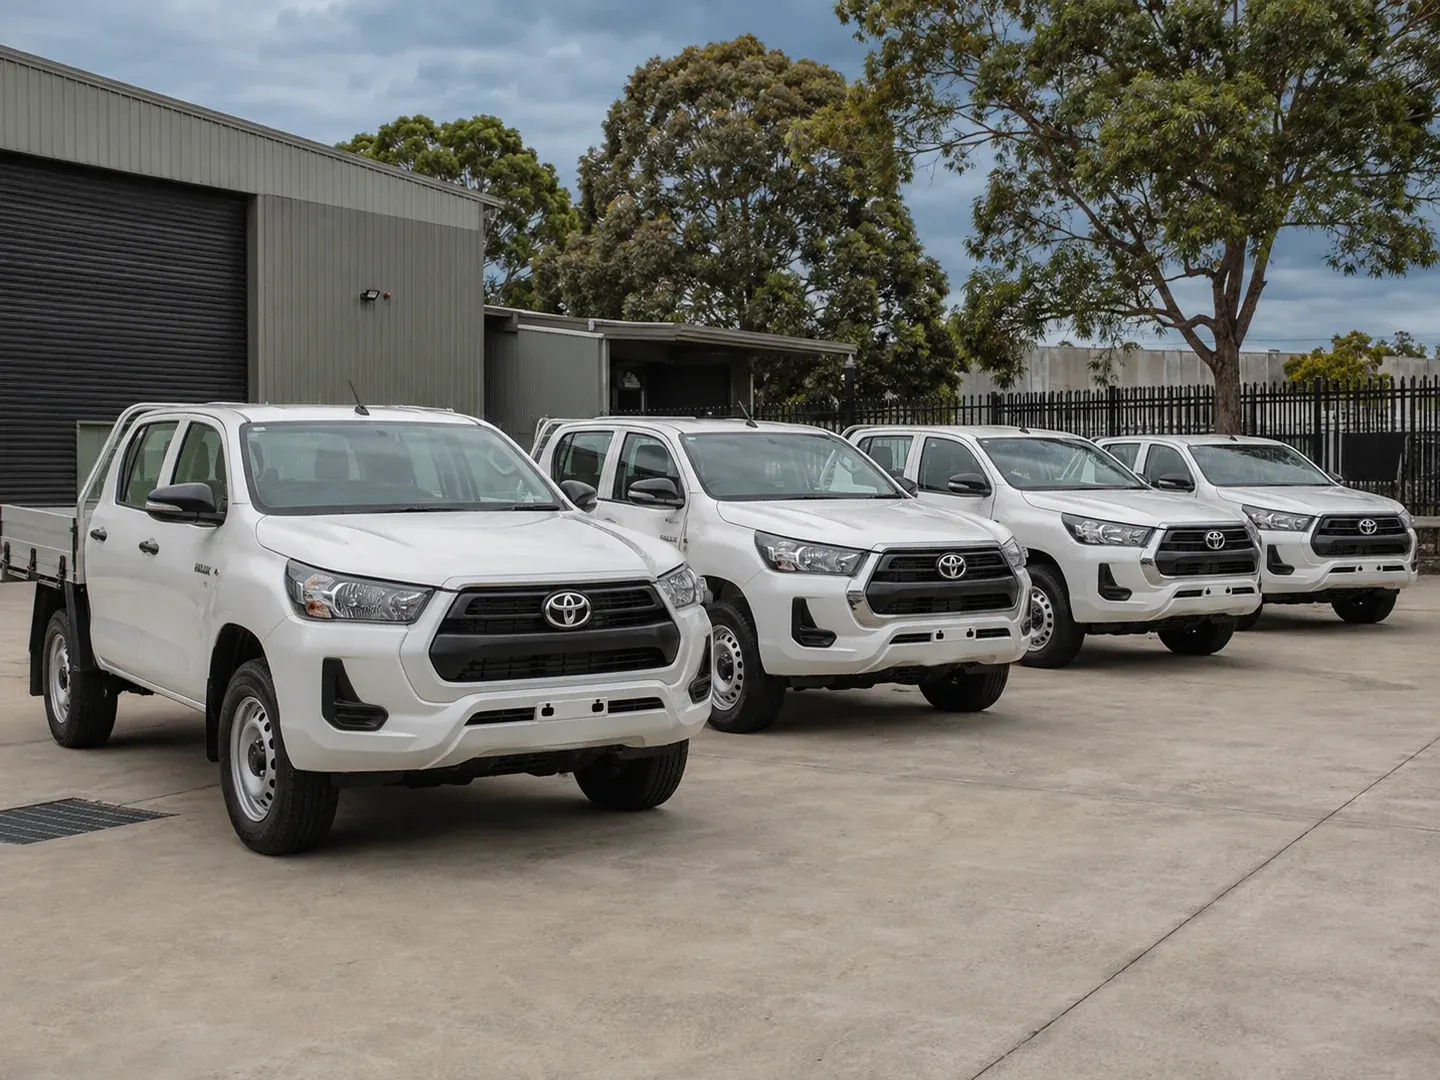
$174,000
Four Hilux vehicles for a company only one month old
All four vehicles were approved on the first lender enquiry and settled at a historical rate of 8.69%, with no deposit and a 30% balloon to preserve project cashflow.
Read the outcome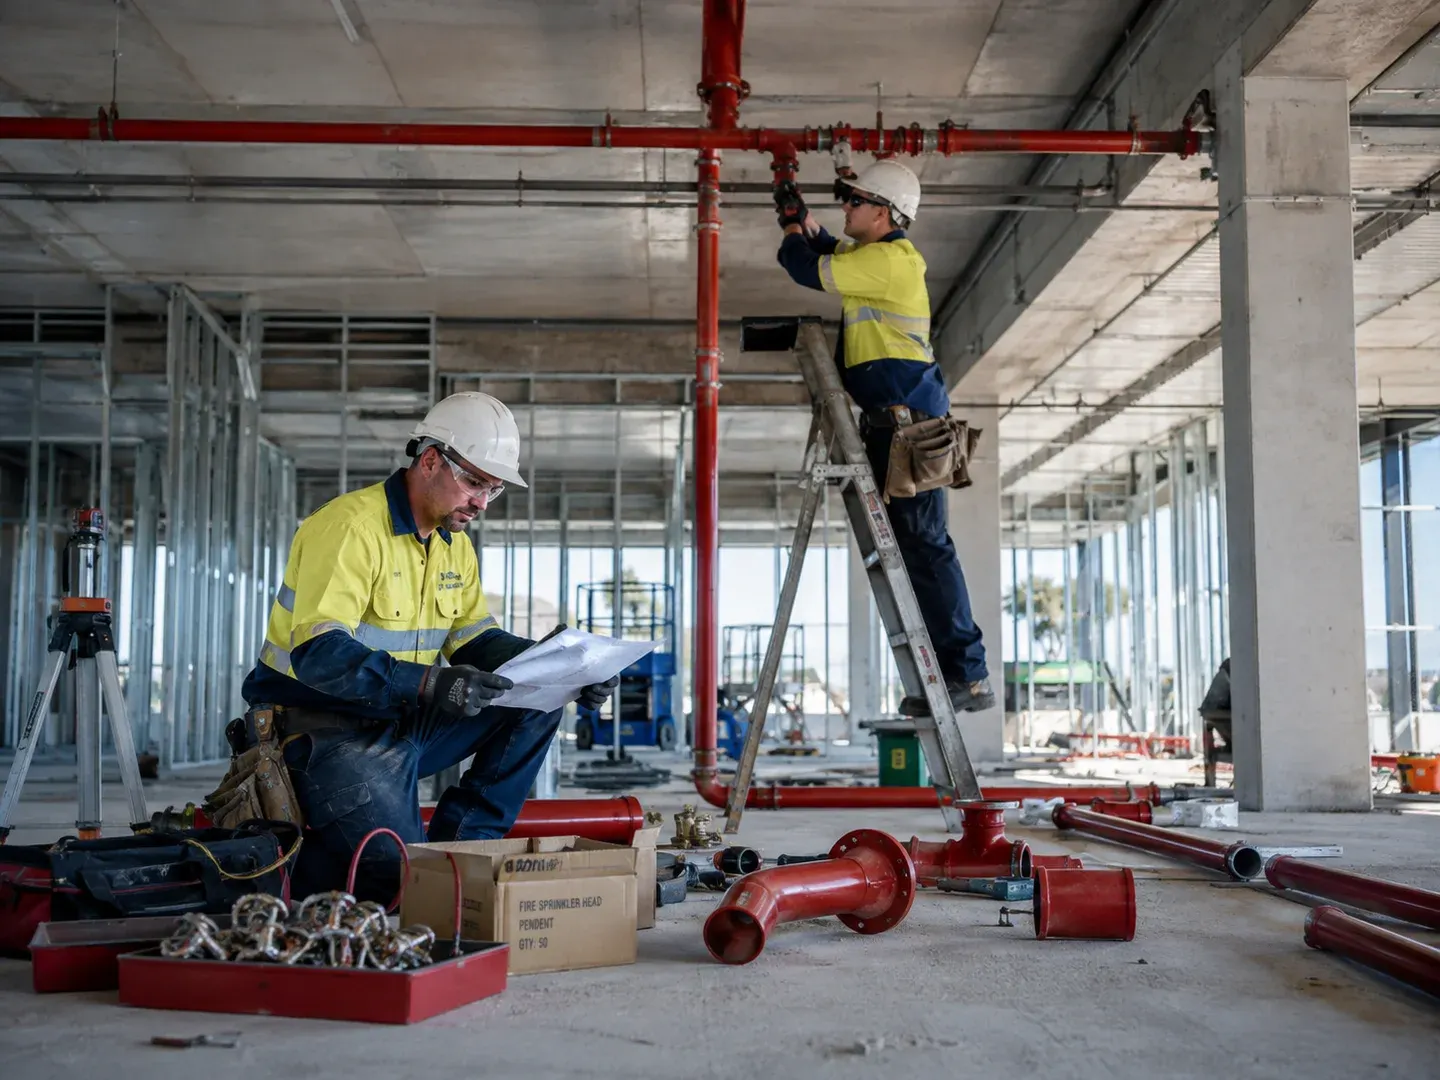
$75,000
Working capital bridged wages and materials during slow payments
Approved on the first lender enquiry and settled for $75,000 at a historical rate of 12.95%, allowing wages and materials to be paid while invoices remained outstanding. The 24-month repayment schedule outlasts a 90-day invoice gap. An invoice payment does not by itself close the loan; any earlier payout follows the facility's terms.
Read the outcome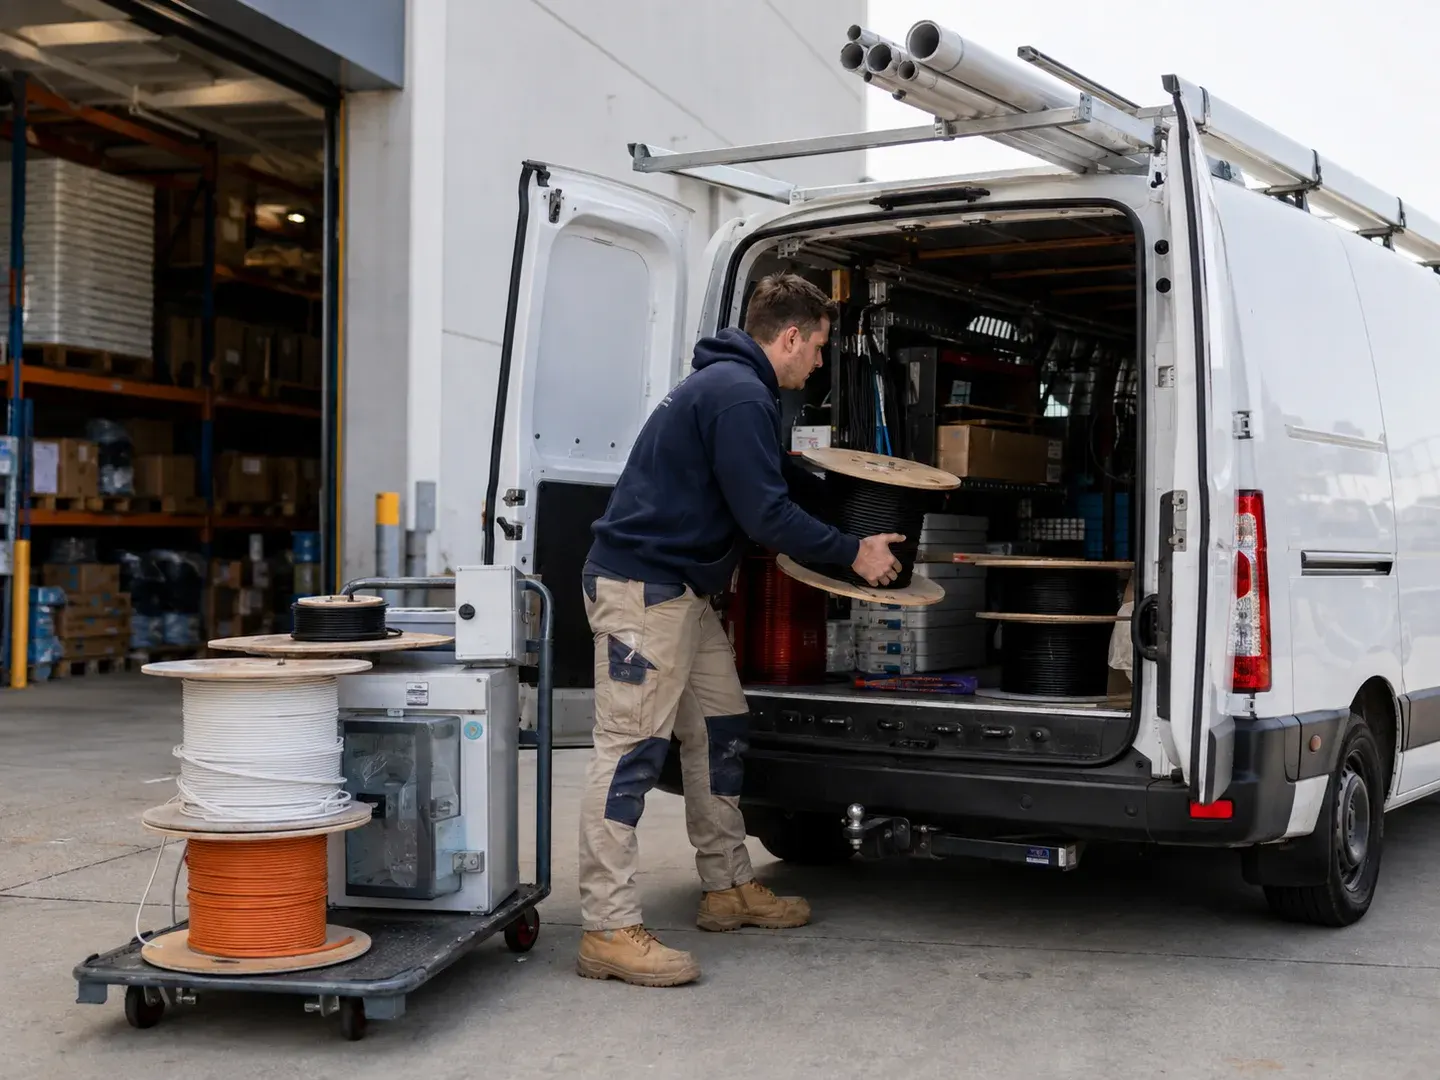
$60,000 limit
A revolving facility funded materials before progress payments
Approved on the first lender enquiry and settled with a $60,000 limit. Interest applied only to the amount in use, creating an ongoing project cashflow buffer. Not included in this anonymised summary: the rate, facility fees and review terms.
Read the outcome