Unsecured Business Loans
Working capital for a fitout, a new store or a marketing push, no property security required.
View finance optionsFitouts, stock, POS and delivery vehicles, one application across 80+ lenders to fund your store and smooth the seasonal peaks.
Google reviewsRead client feedback

Retail is a game of timing: you buy stock before the season, fit out before you open, and wait for sales to catch up. X Lend is a finance broker: we compare a panel of 80+ banks and nonbank lenders and arrange the finance so you can invest in growth without draining the till.
Banks are cautious with retailers and slow to move. We match your situation, including low doc and alternative-document options, to lenders who understand retail: seasonal peaks, thin margins on volume, and the constant pull between holding stock and holding cash.
From a single store fitout or a stock up for the busy season to a second location or a delivery fleet, we structure the finance around your cashflow and get a decision fast. You focus on selling; we handle the paperwork.
From the fitout to the stock on the shelves, most growth costs can be financed. The common ones:
Working capital for a fitout, a new store or a marketing push, no property security required.
View finance optionsBuy stock ahead of the season and cover wages and rent while sales catch up, smooth the peaks and troughs.
View finance optionsA revolving buffer you draw on for restocks and quiet months, interest only on what you use.
View finance options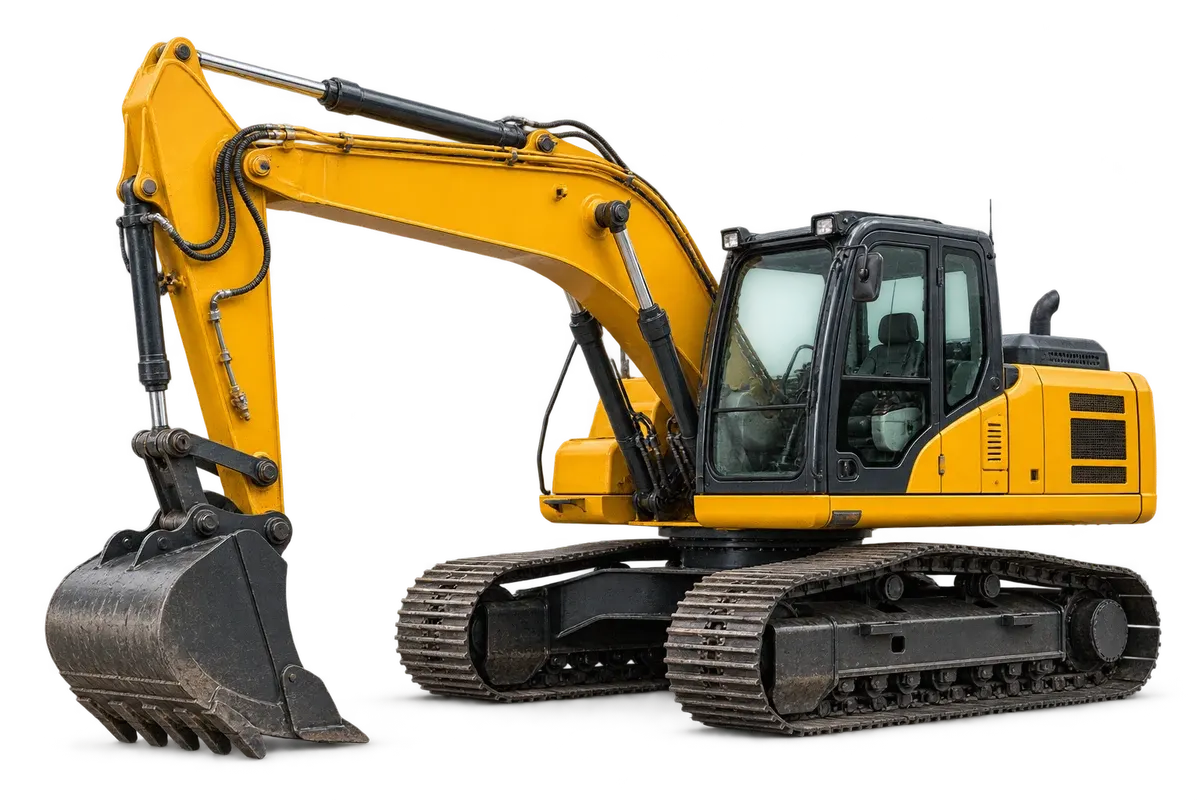
POS systems, fridges, shelving, ovens and fitout equipment, the gear that runs the shop floor.
View finance options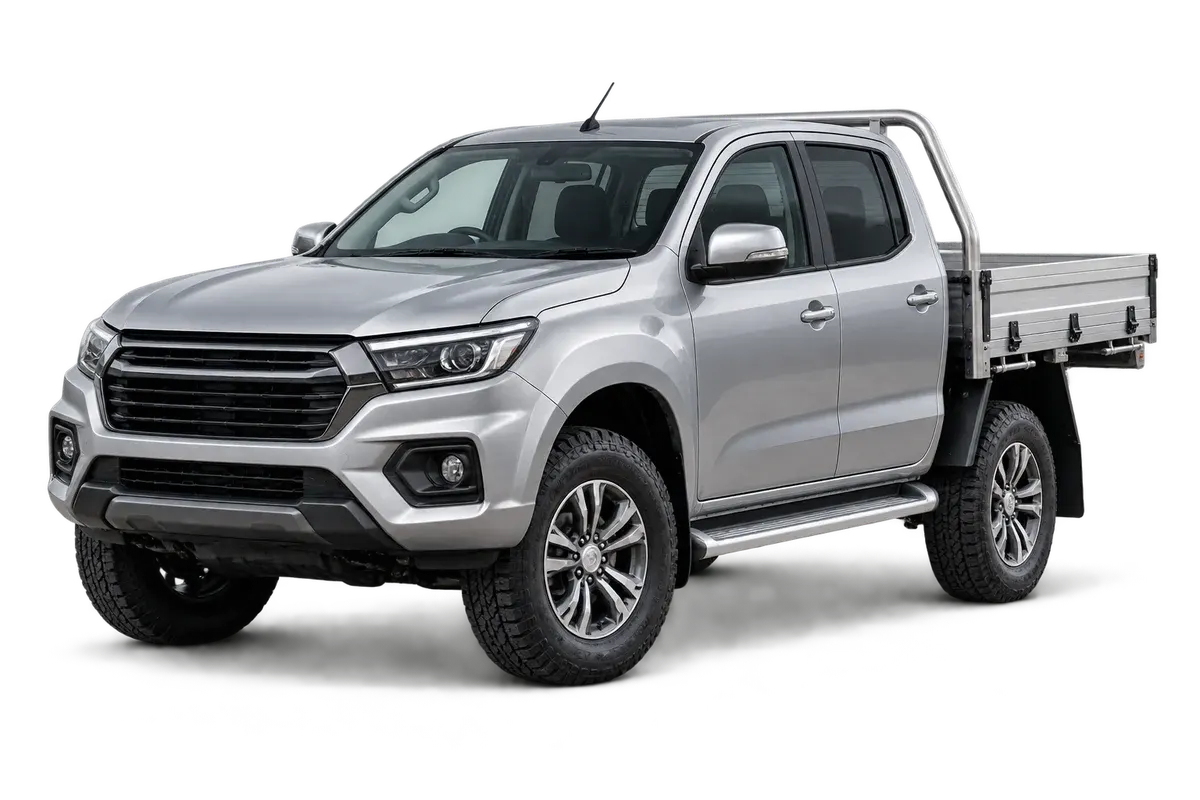
Delivery vans and work vehicles to run click and collect, deliveries and multi site restocks.
View finance optionsFor wholesale and trade supply retailers, turn unpaid invoices into cash instead of waiting on terms.
View finance optionsOne broker to compare our panel of 80+ banks and specialist lenders.
Talk through your optionsWe compare banks and specialist lenders in one go to find the sharpest rate and structure for your store.
Established ABNs can often access finance without full financials, quick and light on paperwork.
We match you to lenders who get retail's peaks and troughs and structure repayments to suit.
Stock deadlines and fitout timelines don't wait, your broker checks the funding timeline against your deadline.
Finance the fitout and stock so your own cash stays free for the things that drive sales.
We handle the lender, the paperwork and the settlement so you can run the shop.
The right finance should support the work ahead. Compare what it makes possible with the cost and commitment of borrowing.
Access vehicles and equipment for new contracts, replacements or a growing workload.
Spread an eligible purchase over time while keeping a buffer for wages, materials and operating costs.
Replace unreliable assets when the cost of repairs and lost working time starts adding up.
Compare interest, fees and any final balloon payment alongside the total amount you will repay.
Repayments continue when work slows or customers pay late. Check the commitment against your cashflow.
Weigh repair costs and missed work against the cost of finance. Paying cash also reduces your available buffer.
business.gov.au recommends keeping inventory records that show stock on hand, what is selling and when to reorder. Regular reviews help identify slow-moving stock and avoid unnecessary costs.
business.gov.au: managing inventoryFor a stock purchase, compare supplier payment dates with realistic sell-through and customer receipts. Separate a seasonal timing gap from consistently weak margins. For a fit-out, allow for deposits, approvals and the period before the shop reopens or reaches normal trading.
Source checked 5 September 2026. These planning points explain how to prepare; lender requirements and regulatory obligations depend on your circumstances.
Get clear on eligibility, paperwork and the next steps before you apply.
Ask a brokerWe're a finance broker: we compare a panel of 80+ banks and nonbank lenders and arrange the finance with the one that best fits your retail business.
Yes. Fitouts can be funded through equipment finance or an unsecured business loan, often under one facility, structured around your cashflow and opening timeline.
That's a common one. We arrange cashflow finance and lines of credit so you can buy stock ahead of demand and repay as it sells. Working-capital timing depends on lender assessment and complete documents.
Often, yes. Our nonbank lenders consider newer businesses and situations the majors decline. We're upfront about what's realistic before you apply, so you don't waste a credit enquiry.
Getting an indicative quote doesn't touch your credit file. A formal application involves a credit check, but we only lodge once you're happy to proceed.