80+ lenders, one application
We compare new-car policies across banks and specialist lenders, including delivery timing, deposit and trade-in treatment.
The first drive. The new-car feeling. Explore our 80+ lender panel, with your broker handling the finance search and paperwork for your upgrade.

If it's rolling off a dealership floor, there's usually a sharper deal to be had. We regularly arrange finance for:
Brand new cars from a franchise dealership
New SUVs, utes and 4WDs
New electric and hybrid vehicles
Factory ordered and build to spec vehicles
Drive away and on road costs included deals
Trade-in plus finance on the balance
No deposit and balloon structures
Refinancing a dealer loan onto a better rate
These new car examples are not a restricted list. Age, condition, value and suitability as loan security generally matter more than the badge.
The new car finance process and paperwork change depending on whether the new car comes from a dealer, private seller or an existing loan being refinanced.
These records help confirm income, identify the new car and reconcile the amount that must be paid at settlement.
Have something in mind? Let’s talk finance.
Get my free quoteThere's nothing like driving a brand new car off the lot, but the finance desk shouldn't decide your budget for you. X Lend is a finance broker: we take one application and compare it across a panel of 80+ banks and nonbank lenders to find the sharpest rate your profile can actually get on a new vehicle.
We compare new-car policies across banks and specialist lenders, including delivery timing, deposit and trade-in treatment.
Know your exact budget and walk into the showroom as a cash buyer, with finance ready before you talk numbers.
Compare our offer with the dealership's on the same term, fees and total-cost basis, then choose the stronger deal.
The smartest move with a new car is to sort your finance before you set foot in the showroom. When we get you preapproved, you know your exact budget and you negotiate the drive away price like a cash buyer, with none of the pressure to sign whatever the dealer's finance desk puts in front of you. Then you can compare that offer against ours, line by line, and pick the better deal with clear eyes.
Our accredited panel gives you access to several lender options. We explain every number in plain English, show the headline and comparison rates, and submit only after you choose to proceed. An initial quote leaves your credit file untouched.
For a new car, we show the interest rate, comparison rate, financed fees, balloon and total repayment on the same term.
Many new car applications get a decision the same day, with settlement often ready before your delivery date.
Pick a term that suits your budget, review available deposit and balloon options, and understand every early-exit condition before proceeding.
Dealer offering zero percent finance? It can be a genuine deal, or it can be baked into a higher car price. We'll help you compare the true drive away cost against a straight loan so you know which one actually saves you money.
Try an amount and term for your car loan. When you’re ready, we’ll compare the options available to you.
Adjust the amount, term and rate to see an indicative repayment.
Estimate only. Calculations include an assumed $990 broker origination fee and $500 lender fee, both financed. Total repayable includes those fees, interest and any final balloon. Weekly and fortnightly figures are equivalents of the monthly estimate. Actual fees and repayment timing depend on your offer.
Your quote takes your circumstances and finance requirements into account. Compare your rate, fees and repayments together before choosing an offer.
Find my optionsThe customer had only been in a casual PAYG role for two months. Their partner was not working, they had two dependent children and they had no previous PAYG employment history to demonstrate continuity.
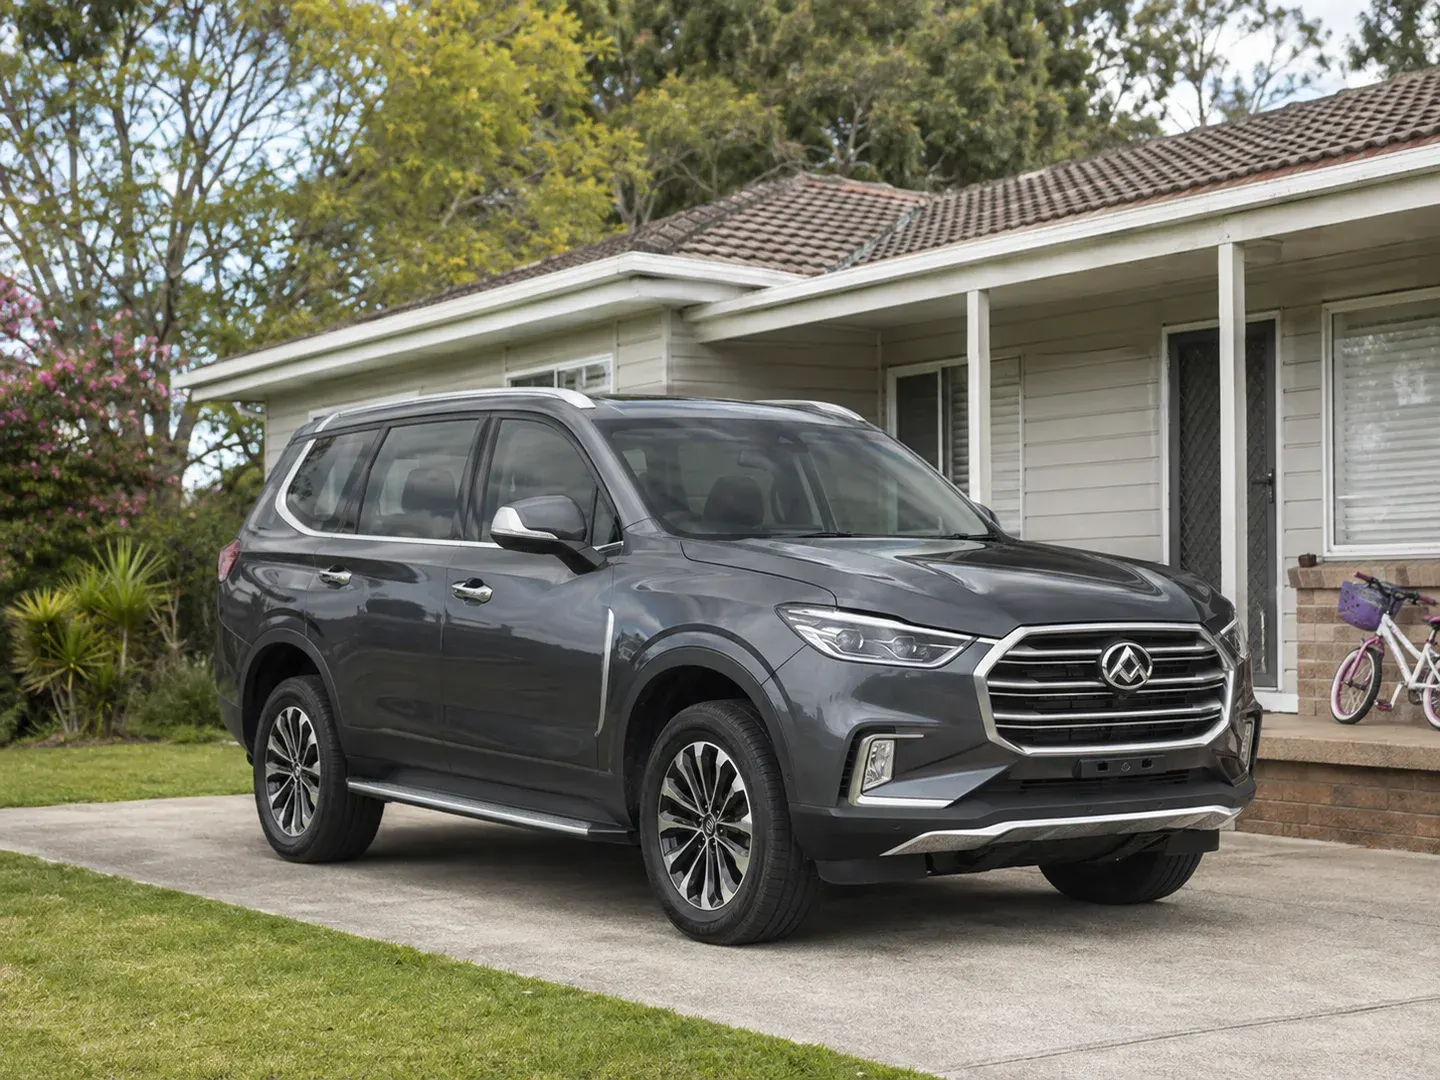 New car finance · Sydney, NSW
Approved on the first lender enquiry and settled for the full $39,000 at a historical rate of 8.5%, with no deposit required.
Historical customer outcome. Vehicle and business images are illustrative.
Find out what’s possible for you.
Get my free quoteNew cars sail through lender policy more easily than anything else on the road, the assessment is really about you. Here's what lenders typically look at, and what to have ready.
Dealerships sometimes shop one application to several lenders at once, leaving a trail of enquiries that spooks the next bank. We do the comparing before anything is lodged, so your file only sees one application, with the right lender.
A job still in probation or recently started casual work can trip lenders that want a longer track record. Others on our panel are comfortable with a shorter history, and if none fit today, a couple more pay cycles often changes the answer.
When the budget is close, small changes matter: a trade-in or deposit, reducing unused credit card limits, a longer term or a slightly different spec can all bring the numbers back into range.
A brand new car is often someone's first big loan, and some banks see a blank credit history and hesitate. Other lenders weigh your income and banking conduct more heavily, and a deposit strengthens the picture further.
For new car finance, a lender assesses the specific new car, the purchase or refinance transaction and whether the proposed repayments fit the applicant's verified budget. The sections below show how those checks connect.
Your broker handles the lender comparison and paperwork for car loan, keeping you informed at each step.
Tell us what you want to finance, how much you need and when you need it. That could include brand new cars from a franchise dealership.
We help organise driver licence (front and back) and your two most recent payslips and check a current Australian driver licence to find lenders that fit your situation.
We explain fixed rate secured car loan and balloon or residual payment, including the full cost and how repayments fit your budget. You choose the option to take forward.
Your broker coordinates lender conditions, signed documents and payment details, so you can focus on what comes next.
Your broker reviews your enquiry and explains the next steps, usually within one business day. An enquiry does not create a credit check or an obligation to proceed.
A brand new car is the easiest vehicle to finance well, and there are a few ways to shape the loan around your budget:
The go to for new cars: the vehicle acts as security, which typically earns the sharpest rates on the market, and your repayments stay the same for the life of the loan.
Popular on new cars, a lump sum is set aside until the end of the term, lowering your monthly repayments. When it falls due, you can pay it out, refinance it or sell the car, which suits buyers who upgrade every few years.
Many lenders will fund the full drive away price on a new vehicle, so you don't have to drain savings to get the keys. A deposit remains an option if you'd rather shrink the repayments.
Shorter terms cost less in total interest; longer terms ease the monthly budget. We match the term to how long you actually plan to keep the car, depending on what the lender offers.
Your trade-in acts as an effective deposit. If the old car still has money owing, the payout is handled as part of settlement and you only finance the difference.
Swipe across the table to compare all columns.
| Option | During the loan | At the end |
|---|---|---|
| No balloon | Higher regular repayments than the same loan with a balloon; the balance reduces faster | The scheduled loan balance is repaid when all payments have been made. |
| A balloon payment | Lower regular repayments, but interest is charged on a larger outstanding balance | A lump sum remains due. Budget for it rather than assuming resale or refinancing will cover it. |
| A shorter term | Higher regular repayments may reduce total interest on otherwise equal terms | Check affordability alongside the total amount repaid, fees and any payout costs. |
Use the calculator to compare the same amount, rate and term with and without a balloon. Refinancing requires a new assessment and is not guaranteed.
A discount, contribution or low headline rate can be offset elsewhere in the transaction. The useful comparison is the final vehicle price and total amount repayable.
Ask for the drive-away price with and without the finance promotion so the two parts can be compared.
It can lower regular repayments but creates a larger final obligation and may affect equity at trade-in.
Review each insurance product, warranty, accessory and protection package individually before including it in the loan.
A long wait may mean documents, valuations or approval conditions need updating before settlement.
New vehicles usually provide a clear valuation reference. Delivery timing, model-year changes, optional accessories and a trade-in payout can change the final amount required at settlement. In practice, those details can change the available lenders, the deposit required and the longest loan term offered.
For new car finance, a balloon leaves part of the amount as a lump sum due at the end. It can reduce regular repayments, but the final amount must still be paid or refinanced, so we compare both the repayment effect and total cost.
A dealer invoice usually puts the new car and seller details in one place. A private sale adds seller, ownership and Personal Property Securities Register checks; a refinance instead needs a current payout letter showing the existing balance.
The new car finance assessment then reconciles price, deposit, trade-in and any current payout with verified income, living costs and other debts to test whether the proposed repayment fits.
Illustrative examples of how we approach car loan.
The buyer has found a suitable vehicle through a private seller and needs a secure settlement process.
We confirm the seller, vehicle, PPSR status and payout position, then coordinate lender payment instructions with both parties.
Seller identification, registration details, VIN, purchase agreement, payout letter where relevant and the buyer's income documents.
The applicant has moved into a new role with stable current income and a limited history in that position.
We review the employment type, probation terms and continuity of occupation, then compare lenders whose employment policy fits the verified position.
Employment contract, recent payslips, bank credits and evidence of prior work in the same field.
Older credit events appear on the file while recent banking conduct and income show a stronger current position.
We explain the event, confirm its status and present the current income and expense evidence to lenders that assess the complete credit story.
Credit report, proof of payment or release, recent bank statements, payslips and a written explanation of the circumstances.
At X Lend, we first make the purchase amount, purpose and comfortable repayment clear. We then compare suitable panel options on the same term and fee basis, explain the total cost and ask the customer to approve the selected lender submission.
Let’s compare your options.
Get my free quoteSee how arranging finance compares with waiting or paying the full cost upfront.
Access a suitable new car without waiting to save the full purchase price.
Keep more savings available for emergencies after arranging the new car.
Replace an unreliable or unsuitable new car before downtime and repair costs increase.
Work, family commitments or travel can remain disrupted without a reliable new car.
An older new car can keep creating downtime or repair costs while its replacement is delayed.
Paying the full new car purchase price from savings can leave less buffer for unexpected expenses.
Corey was excellent to deal with. He was able to get me a better rate than everyone else, he was very responsive, worked quickly and made the process very easy, even with me asking a million questions. I would definitely use him again next time.
I can’t recommend Corey from X Lend highly enough. From the very first conversation, he was professional, transparent, and genuinely focused on finding the best outcome for me. Corey took the time to explain every step of the finance process in a way that was easy to understand, answered all my questions promptly, and never once made me feel rushed or pressured. I really appreciated how proactive he was, keeping me updated, following up with lenders, and making sure everything stayed on track. What really stood out was how hard he worked to secure a great deal. He compared multiple lenders, negotiated on my behalf, and ultimately achieved a rate and repayment structure that exceeded my expectations. The whole process of purchasing my car was smooth and stress‑free thanks to their expertise. If you’re looking for someone knowledgeable, reliable, and genuinely in your corner, I wouldn’t hesitate to recommend them. I’ll definitely be using their services again in the future :)
Corey helped me through the entire process of getting my dream family car! He was extremely prompt with his responses and had everything organised quickly and smoothly. I made a huge mistake by settling finance on the wrong car (a 5‑seater instead of a 7‑seater), but Corey was incredibly understanding and supportive. He contacted the dealership, lender, and even rearranged my insurance for me. He did all of this without ever making me feel like a hassle, even though I knew I was being a pain! Despite the setback, Corey stayed fast and efficient, kept me confident throughout the process, and managed to get everything cancelled and re‑approved for a higher amount so I could get my actual dream car. I highly recommend Corey. He speaks to you like a friend and genuinely has your best interests at heart. I already had quotes from Toyota Finance and Toyota Insurance, and Corey was able to get both significantly cheaper. Toyota Finance even reviewed Corey’s figures and confirmed they couldn’t beat them. I will never look to another finance company again.
Let us help with
car loan.
The details you want to know before taking the next step.
We're a finance broker: we compare a panel of 80+ banks and nonbank lenders and place your new car loan with the one offering the best fit and rate for your situation.
It pays to compare both. Dealer finance is convenient, but the rate isn't always the sharpest and the offer can be tied to a higher car price. We get you preapproved so you can put our deal next to theirs and simply pick whichever costs you less.
Pre approval tells you your exact budget and lets you negotiate the drive away price like a cash buyer. You're no longer at the mercy of the finance desk, and you can commit to a car knowing the money is already sorted.
Sometimes. A genuine zero percent deal can be great, but the cost is occasionally built into a higher purchase price or fewer discounts. We help you compare the true drive away cost against a standard loan so you see which one actually wins.
No. An indicative quote from us doesn't touch your credit file. A formal application involves a credit check, but we only lodge with a lender once you're happy to go ahead.
It varies by lender, but pre approvals typically hold for somewhere between one and three months, usually plenty of time to choose a car and negotiate. If yours lapses while you're waiting on a factory order, we simply refresh it before delivery.
It can be. A balloon lowers your monthly repayments by leaving a lump sum to the end of the term, which suits buyers who upgrade every few years, the car's value at trade-in often covers it. If you plan to keep the car long term, a straight loan is usually simpler. We'll map out the total cost of both so you can choose with clear eyes.
Yes, this happens all the time. The dealer's trade-in offer goes towards paying out your existing loan, and the new loan covers the balance of the purchase. If the payout is larger than the trade-in value, the shortfall can often be included in the new loan, we'll walk you through exactly how the numbers land.
Generally, yes. Many lenders will fund the full drive-away price, including registration, stamp duty and dealer-fitted accessories, depending on the lender and vehicle. Send us the complete quote and we will structure the request around every included cost.
Common examples include Toyota, Ford, Mazda, Hyundai, Kia, Mitsubishi. This is not a restricted list: the lender will still look at the exact item or purpose, the amount requested and your circumstances.
A lender may ask for dealer tax invoice, build or order sheet, deposit receipt, payslips, bank statements, trade-in and payout details. You may not need everything on that list. X Lend confirms what applies before anything is submitted.
For car loan, we first confirm the transaction, timing and available evidence. We then explain the issues that matter, compare lenders whose rules fit those facts and show the proposed option before any application is submitted.
Reviewed by Corey Marino
FBAA member M-354085 · Diploma-qualified finance broker · Last reviewed 24 August 2026