80+ lenders, one application
We compare commercial and asset lenders in one go to match your gear to the sharpest available rate.
Bring your venue’s next chapter to life. Your broker searches our 80+ lender panel for suitable equipment finance and helps organise the paperwork.

If it helps you serve, we can usually finance it. We arrange finance for:
Commercial kitchens, ovens and cooktops
Espresso and automatic coffee machines
Cool rooms, freezers and refrigeration
Dishwashers and glasswashers
Bar, tap and beverage systems
Front of house, POS and ordering technology
Furniture, joinery and venue fitouts
Used and ex venue equipment
These hospitality equipment examples are not a restricted list. A lender will usually place more weight on the chosen asset's age, condition, specification and intended work than its badge.
The way this hospitality equipment is being purchased affects the lender's valuation, available term and security checks.
These records connect the hospitality equipment, its total cost and intended work with the business's ability to make the repayments.
Have something in mind? Let’s talk finance.
Get my free quoteA cafe or restaurant lives on its equipment, the kitchen, the machine, the cool room, but a fitout shouldn't swallow every dollar before you've served a single cover. X Lend is a finance broker: we take one application and compare it across 80+ banks and nonbank lenders so you can kit out the venue and keep a float for stock, staff and the quiet first weeks.
We compare commercial and asset lenders in one go to match your gear to the sharpest available rate.
We can bundle kitchen, refrigeration and the venue fitout into a single facility.
We arrange finance for new, used and ex-venue equipment across suitable purchase channels.
We arrange finance for commercial kitchens, espresso and coffee machines, ovens and cooktops, cool rooms and refrigeration, dishwashers, bar and front of house gear, and complete venue fitouts, new or used, single items or the whole build. We structure it as a chattel mortgage, hire purchase or rental to suit your GST, depreciation and accountant's advice.
Because we shop the whole panel, we can bundle equipment with the fitout into one finance option, place used and ex venue gear that a single bank might pass on, and match low doc options to how your venue trades. We keep it plain English and only submit once you're ready.
Established venues can often finance significant equipment without full financials.
Hospitality equipment can be owned or rented under different structures; compare cash flow and flexibility before confirming tax treatment with the venue's accountant.
Many hospitality deals settle in 48 to 72 hours so the venue opens sooner.
Equipment and fitout costs can frequently be combined into a single finance option with one repayment. Established ABNs can often access low-document pathways using trading history, with many deals settling within 48 to 72 hours.
Try an amount and term for your hospitality equipment finance. When you’re ready, we’ll compare the options available to you.
Adjust the amount, term and rate to see an indicative repayment.
Estimate only. Calculations include an assumed $990 broker origination fee and $500 lender fee, both financed. Total repayable includes those fees, interest and any final balloon. Weekly and fortnightly figures are equivalents of the monthly estimate. Actual fees and repayment timing depend on your offer.
Your quote takes your circumstances and finance requirements into account. Compare your rate, fees and repayments together before choosing an offer.
Find my optionsThe business needed equipment from several suppliers while retaining enough cash to cover wages, opening stock and the other costs of launching a second venue.
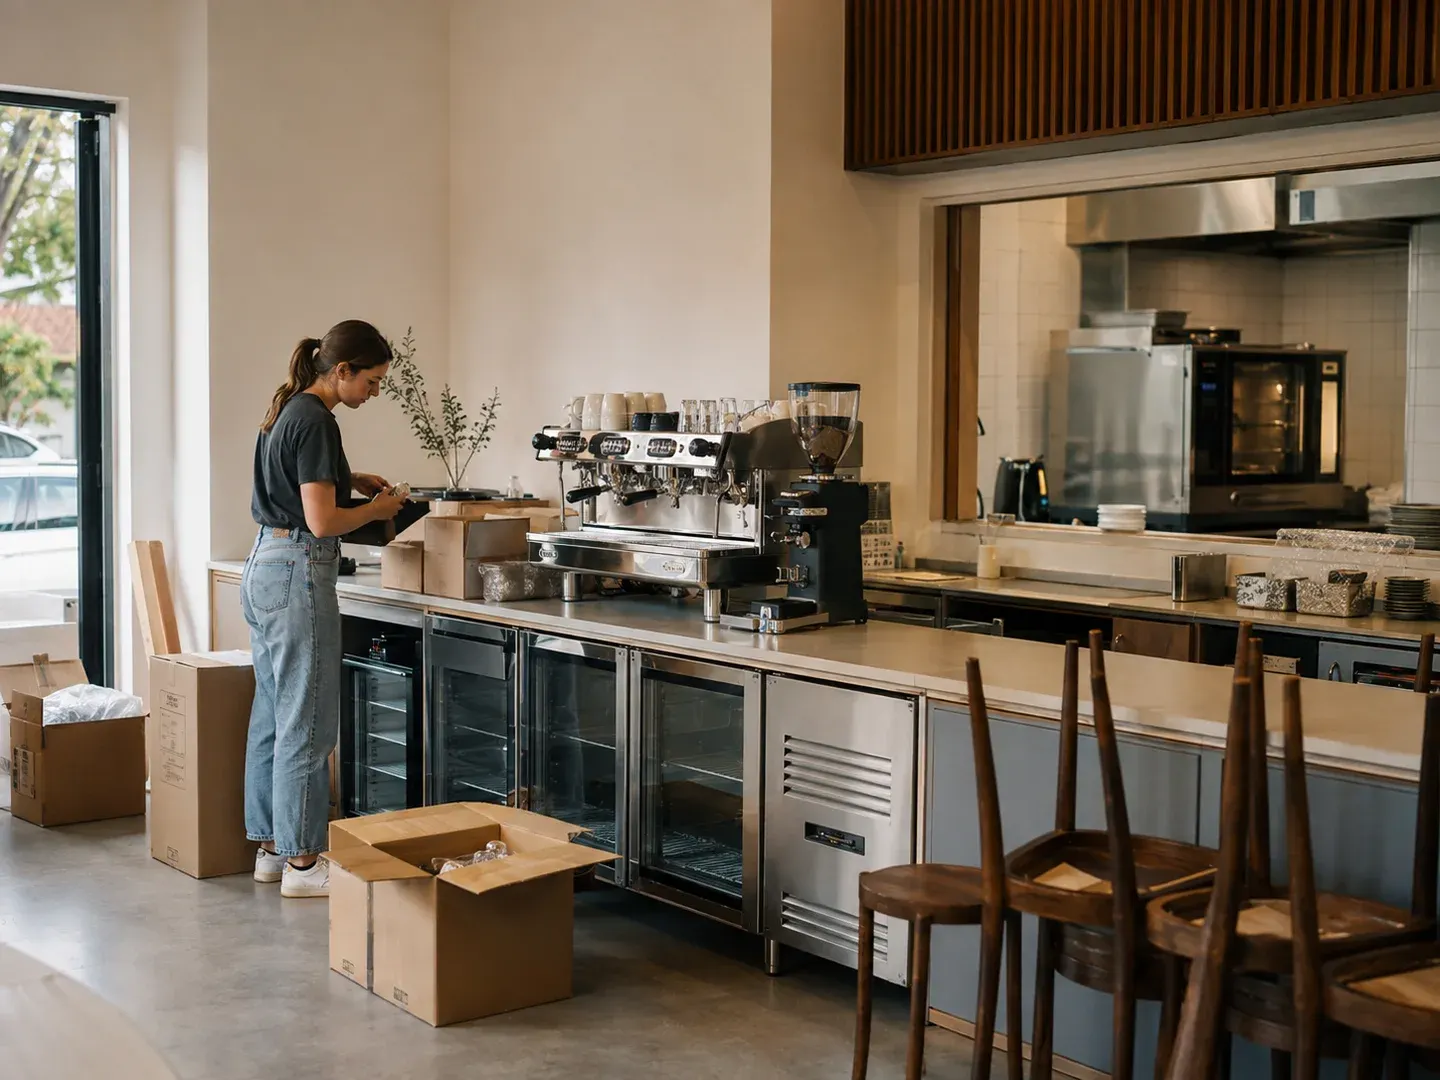 Hospitality equipment finance · Melbourne, VIC
Approved on the first lender enquiry and settled at a historical rate of 9.25%. Every supplier was paid and the second café opened without draining operating cash.
Historical customer outcome. Vehicle and business images are illustrative.
Find out what’s possible for you.
Get my free quoteWe match your circumstances to suitable lenders for hospitality equipment finance. Your broker helps you prepare the application.
A lender wants to know what the hospitality equipment is, what it will do for the business, how long it should remain useful and whether the repayments are affordable. The details below explain the usual checks and what can help support the application.
Your broker handles the lender comparison and paperwork for hospitality equipment finance, keeping you informed at each step.
Tell us what you want to finance, how much you need and when you need it. That could include commercial kitchens, ovens and cooktops.
We help organise supplier quotes and fit-out schedule and check the lender criteria that apply to your circumstances to find lenders that fit your situation.
We explain the available rate, term, repayment and security options, including the full cost and how repayments fit your budget. You choose the option to take forward.
Your broker coordinates lender conditions, signed documents and payment details, so you can focus on what comes next.
Your broker reviews your enquiry and explains the next steps, usually within one business day. An enquiry does not create a credit check or an obligation to proceed.
Compare the ways you can arrange hospitality equipment finance, with a broker to explain your options.
Swipe across the table to compare all columns.
| Option | During the loan | At the end |
|---|---|---|
| No balloon | Higher regular repayments than the same loan with a balloon; the balance reduces faster | The scheduled loan balance is repaid when all payments have been made. |
| A balloon payment | Lower regular repayments, but interest is charged on a larger outstanding balance | A lump sum remains due. Budget for it rather than assuming resale or refinancing will cover it. |
| A shorter term | Higher regular repayments may reduce total interest on otherwise equal terms | Check affordability alongside the total amount repaid, fees and any payout costs. |
Use the calculator to compare the same amount, rate and term with and without a balloon. Refinancing requires a new assessment and is not guaranteed.
A kitchen project often combines financeable equipment with plumbing, electrical work, furniture, signage and opening costs. Itemising each category avoids forcing unlike costs into one facility.
Freight, commissioning, ventilation, plumbing and electrical work may not form part of the secured equipment value.
Age, service history, warranty and parts support can affect both reliability and finance terms.
Supplier delays, approvals and construction dependencies should be reflected in settlement planning.
The business case should connect equipment capacity to the existing or forecast operation without overstating revenue.
Commercial ovens, refrigeration, coffee machines and POS hardware may be identifiable assets, while ventilation, plumbing, electrical work, furniture, signage and opening stock can have different funding treatment. A detailed supplier and contractor budget helps avoid discovering late that part of the project is not covered by the equipment approval.
Coordinate finance timing with approvals, construction and delivery. Rent and wages may begin before the venue trades, so the cash-flow plan should include delays, commissioning and the first stock cycle. Do not assume that a fast equipment approval removes the other dependencies in the opening program.
Choose capacity around a realistic menu, covers and production flow rather than the largest specification available. Check power, gas, water, ventilation, space and cleaning requirements before ordering. A supplier warranty is more useful when local technicians and replacement parts are available during trading hours.
For used equipment, review age, condition, compliance, service history and remaining warranty. An independent inspection can reduce operational surprises. Finance approval does not establish that equipment is safe, compliant or suitable for the premises, and the business remains responsible for those checks.
Model repayments with rent, wages, utilities, merchant fees, food costs and seasonality rather than against turnover alone. New venues and major refurbishments can take time to reach stable trade. Keeping a contingency for delays, repairs and the first operating cycle is generally more resilient than using every available dollar as the deposit.
Operating hours, water quality, temperature cycles, cleaning routines and service support influence commercial kitchen and refrigeration life. In practical terms, this can change the deposit required, how long the loan can run and which lenders will consider the asset.
Compressor servicing, heating elements, seals, water filtration and planned replacement form part of maintenance and replacement spending. These costs need to fit beside the repayments. The loan should also finish within the period the asset is expected to remain useful to the business.
Venue sales, bookings, lease details, menu capacity and opening dates can support the timing and productive use of the equipment. Contracts, purchase orders and confirmed work can help show how the asset is expected to earn money and when customers are expected to pay.
If the hospitality equipment supplier needs a deposit, progress payments and a final payment, list each date and amount. This lets the lender reconcile the full purchase cost and arrange the payment stages correctly.
Illustrative examples of how we approach hospitality equipment finance.
The business has a shorter ABN history and confirmed work that requires the hospitality equipment.
We identify lenders that can assess recent account history, industry experience and contracted work, then present the purchase as one complete operating proposal.
Business bank statements, GST registration, signed work agreements, the supplier quote and evidence of the operator's experience.
The chosen asset has material age, hours or kilometres and remains suitable for the work ahead.
We document condition, service history, specification and resale support, then compare lenders whose end-of-term age policy fits the proposed term.
Service records, inspection details, serial or VIN information, photographs, the invoice and a clear explanation of expected annual use.
Current work supports the purchase while the latest full-year accounts are still being prepared.
We list the documents already available, current debts and expected payment timing, then compare lenders that accept that evidence.
Recent bank statements, BAS, management accounts, an accountant letter, contracts, purchase orders and a schedule of existing finance.
Hospitality projects often mix durable equipment with fit-out and opening expenses. We itemise those costs early, identify what an asset lender can reasonably fund and structure any remaining need separately so the approval matches the actual project.
Let’s compare your options.
Get my free quoteSee how arranging finance compares with waiting or paying the full cost upfront.
Put the hospitality asset needed for suitable work into service without waiting to fund the full cost from cash.
Preserve working capital for wages, materials and tax while arranging the hospitality asset.
Replace an unreliable or unsuitable hospitality asset before downtime and repair costs increase.
Suitable contracts may be missed when the required hospitality asset is not available.
An older hospitality asset can keep creating downtime or repair costs while its replacement is delayed.
Buying the hospitality asset outright can reduce the cash buffer available for payroll, materials and unexpected costs.
Corey was excellent to deal with. He was able to get me a better rate than everyone else, he was very responsive, worked quickly and made the process very easy, even with me asking a million questions. I would definitely use him again next time.
I can’t recommend Corey from X Lend highly enough. From the very first conversation, he was professional, transparent, and genuinely focused on finding the best outcome for me. Corey took the time to explain every step of the finance process in a way that was easy to understand, answered all my questions promptly, and never once made me feel rushed or pressured. I really appreciated how proactive he was, keeping me updated, following up with lenders, and making sure everything stayed on track. What really stood out was how hard he worked to secure a great deal. He compared multiple lenders, negotiated on my behalf, and ultimately achieved a rate and repayment structure that exceeded my expectations. The whole process of purchasing my car was smooth and stress‑free thanks to their expertise. If you’re looking for someone knowledgeable, reliable, and genuinely in your corner, I wouldn’t hesitate to recommend them. I’ll definitely be using their services again in the future :)
Corey helped me through the entire process of getting my dream family car! He was extremely prompt with his responses and had everything organised quickly and smoothly. I made a huge mistake by settling finance on the wrong car (a 5‑seater instead of a 7‑seater), but Corey was incredibly understanding and supportive. He contacted the dealership, lender, and even rearranged my insurance for me. He did all of this without ever making me feel like a hassle, even though I knew I was being a pain! Despite the setback, Corey stayed fast and efficient, kept me confident throughout the process, and managed to get everything cancelled and re‑approved for a higher amount so I could get my actual dream car. I highly recommend Corey. He speaks to you like a friend and genuinely has your best interests at heart. I already had quotes from Toyota Finance and Toyota Insurance, and Corey was able to get both significantly cheaper. Toyota Finance even reviewed Corey’s figures and confirmed they couldn’t beat them. I will never look to another finance company again.
Let us help with
hospitality equipment finance.
The details you want to know before taking the next step.
We're a finance broker: we compare 80+ banks and nonbank lenders and place your hospitality equipment finance with the best fit for your venue.
Often, yes. We can bundle kitchen, refrigeration and venue fitout costs into a single facility with one scheduled repayment.
Usually, yes. Many of our lenders fund used and ex venue gear. We match the equipment's age and type to lenders comfortable funding it.
Often, yes. Established ABNs can frequently access low doc options on trading history. For newer venues we match you to lenders most comfortable with your situation.
Many hospitality deals get a same day decision and settle within 48 to 72 hours once documents are in.
Common examples include Rational, Hobart, Winterhalter, La Marzocco, Nuova Simonelli, Unox. This is not a restricted list: the lender will still look at the exact item or purpose, the amount requested and your circumstances.
A lender may ask for supplier quotes, fit-out schedule, lease, sales history, booking data, bank statements. You may not need everything on that list. X Lend confirms what applies before anything is submitted.
For hospitality equipment finance, we first confirm the transaction, timing and available evidence. We then explain the issues that matter, compare lenders whose rules fit those facts and show the proposed option before any application is submitted.
Reviewed by Corey Marino
FBAA member M-354085 · Diploma-qualified finance broker · Last reviewed 24 August 2026