Hospitality Equipment Finance
Coffee machines, ovens, cool rooms, POS and full commercial kitchens.
View finance optionsCafé, restaurant and venue finance, we compare 80+ lenders for fitouts, equipment and the cashflow that carries you between peaks.
Google reviewsRead client feedback

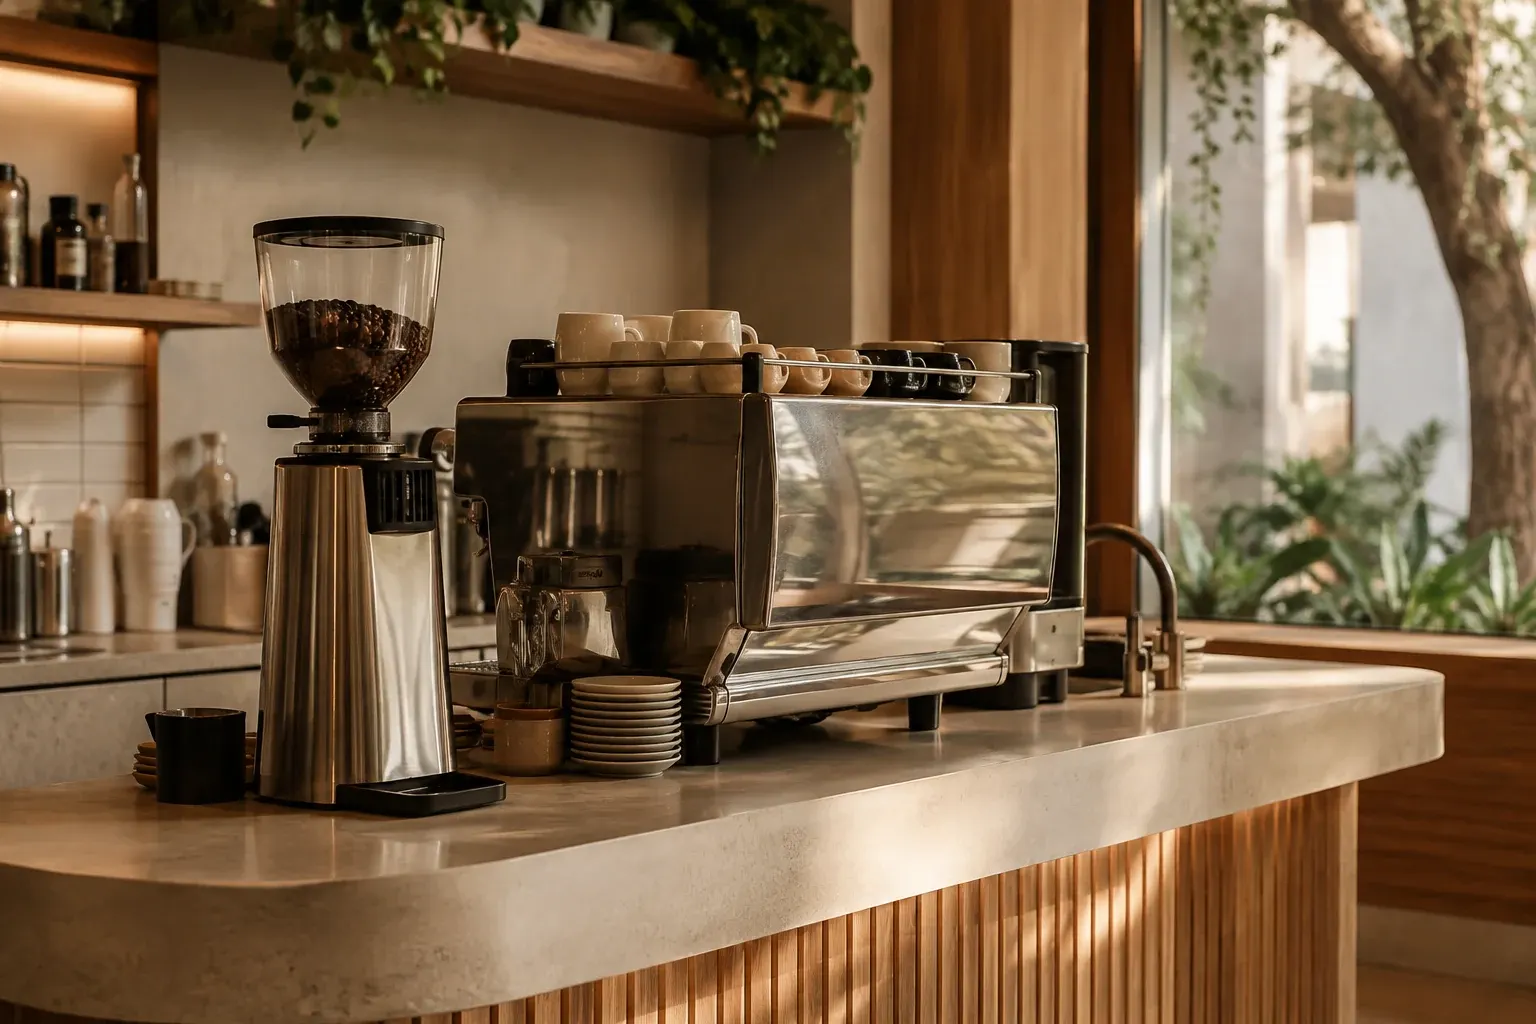
Opening a venue, refreshing a tired fitout, replacing a dead coffee machine before the morning rush, or covering wages through a quiet winter, hospitality is relentless and seasonal. X Lend is a finance broker: we compare a panel of 80+ banks and nonbank lenders and arrange the finance so a cash crunch never closes the doors.
Banks can be wary of hospitality. We aren't, we know which nonbank lenders back cafés, restaurants, bars and function venues, and how to present your numbers (including seasonal and growing businesses) so the deal gets up. Low doc options keep it fast for established operators.
From a single espresso machine to a complete restaurant fitout, plus the working capital to bridge slow weeks and supplier terms, we structure the finance around your cashflow and handle the lender so you can run the floor.
The gear and cashflow a venue runs on, funded to keep your cash for stock and staff:
Coffee machines, ovens, cool rooms, POS and full commercial kitchens.
View finance optionsFund a fitout, refurbishment or second site without putting up property.
View finance optionsCover wages, rent and suppliers through quiet weeks and seasonal dips.
View finance optionsA buffer for stock runs and slow periods, interest only on what you use.
View finance options
Delivery vans and catering vehicles for off site trade and events.
View finance optionsBuying an existing café, restaurant or venue? Fund the purchase and the goodwill.
View finance optionsOne broker to compare our panel of 80+ banks and specialist lenders.
Talk through your optionsWe compare banks and specialist lenders in one go to find appetite for your venue.
Where a bank hesitates, our nonbank panel funds cafés, restaurants, bars and venues.
We present your peaks and troughs to lenders who structure around them.
A dead fryer or a lease deadline can't wait, your broker confirms the steps and timing for the selected lender.
Established ABNs can often finance equipment and fitouts without full financials.
You run the floor; we manage the lender and the settlement.
The right finance should support the work ahead. Compare what it makes possible with the cost and commitment of borrowing.
Access vehicles and equipment for new contracts, replacements or a growing workload.
Spread an eligible purchase over time while keeping a buffer for wages, materials and operating costs.
Replace unreliable assets when the cost of repairs and lost working time starts adding up.
Compare interest, fees and any final balloon payment alongside the total amount you will repay.
Repayments continue when work slows or customers pay late. Check the commitment against your cashflow.
Weigh repair costs and missed work against the cost of finance. Paying cash also reduces your available buffer.
Food Standards Australia New Zealand's Standard 3.2.3 addresses the design of food premises, fittings and equipment. The layout should help minimise contamination; check the details with your local food regulator.
FSANZ: food safety standards for premises and equipmentA kitchen upgrade can involve plumbing, ventilation, electrical capacity and installation as well as appliances. Obtain a complete quote and allow for downtime, opening stock, wages and rent. Compare repayments with achievable service capacity and margins, including quieter weeks.
Source checked 5 September 2026. These planning points explain how to prepare; lender requirements and regulatory obligations depend on your circumstances.
Get clear on eligibility, paperwork and the next steps before you apply.
Ask a brokerWe're a finance broker: we compare a panel of 80+ banks and nonbank lenders and arrange the finance that best fits your hospitality business.
Often, yes. Hospitality is exactly where the nonbank panel earns its keep. We take your numbers to lenders who back venues and know how to read seasonal trade.
Yes. Fitouts are commonly funded via equipment finance or an unsecured business loan, so you can open or refurbish without tying up property.
Yes. We arrange acquisition finance structured around the business you're buying, including goodwill, often serviced partly by the venue's own trade.
Decision and settlement timing depend on the lender, complete documents and any required asset checks. Your broker confirms the expected steps before you commit.
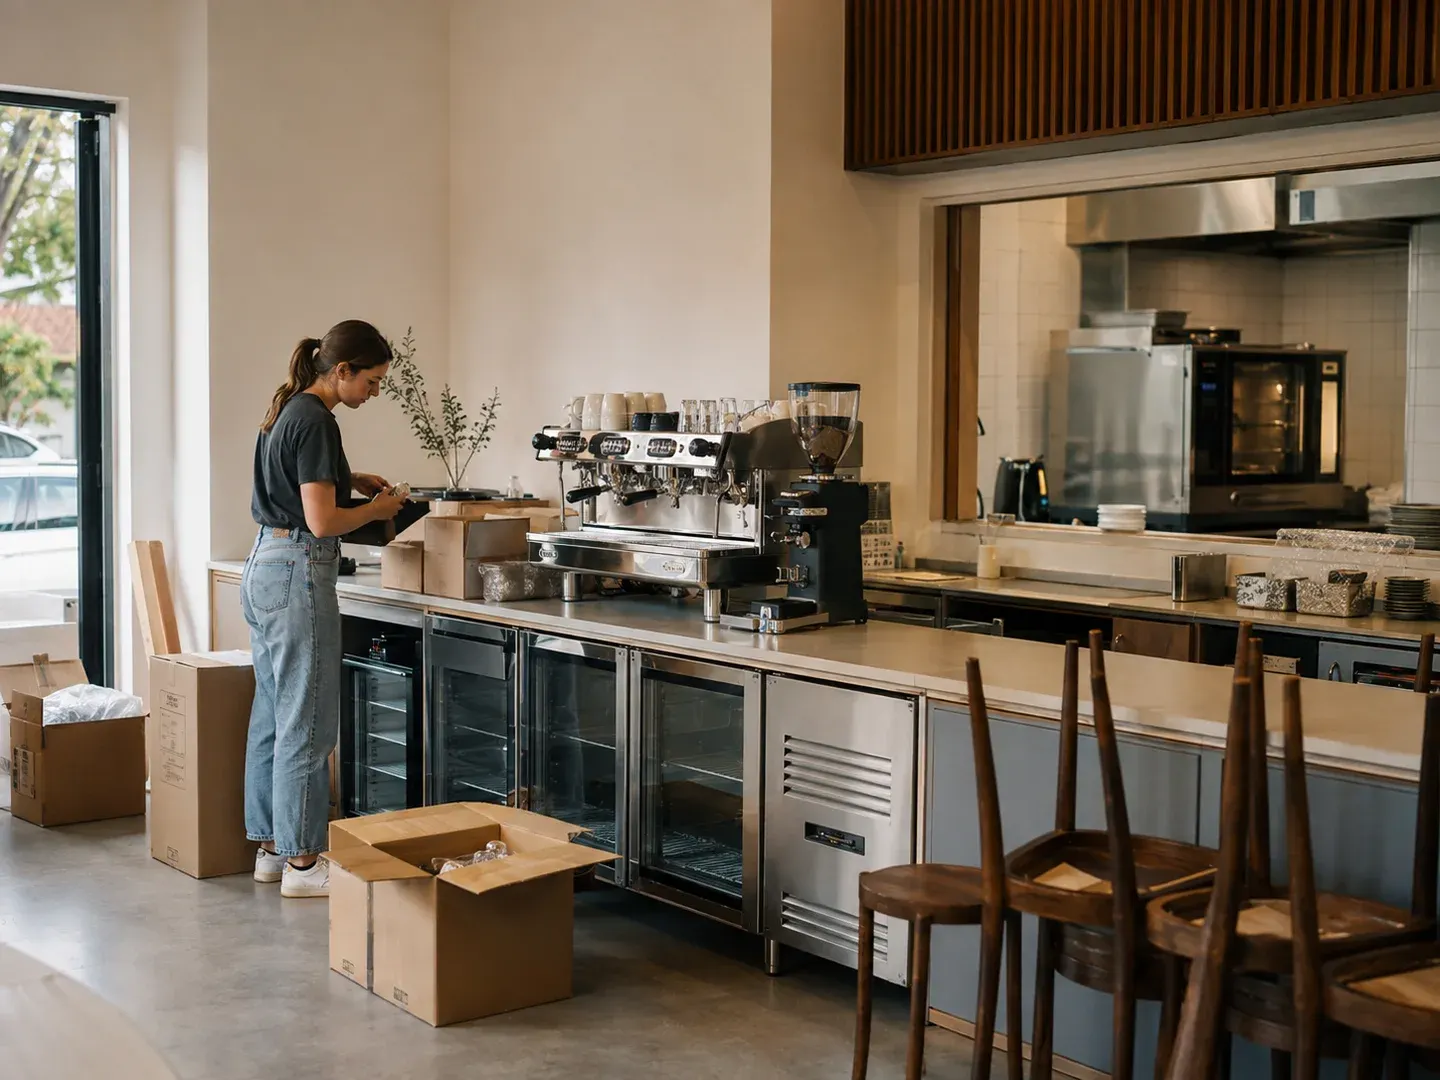
$65,000 settled
Approved on the first lender enquiry and settled at a historical rate of 9.25%. Every supplier was paid and the second café opened without draining operating cash.
Read case study